Conway, SC Real Estate News 

Century 21 McAlpine Blog

The Agents and Staff at Century 21 McAlpine love our area and one another! We hope to share some of our daily activities with you and see how we might better serve our community!


Sept. 7, 2026

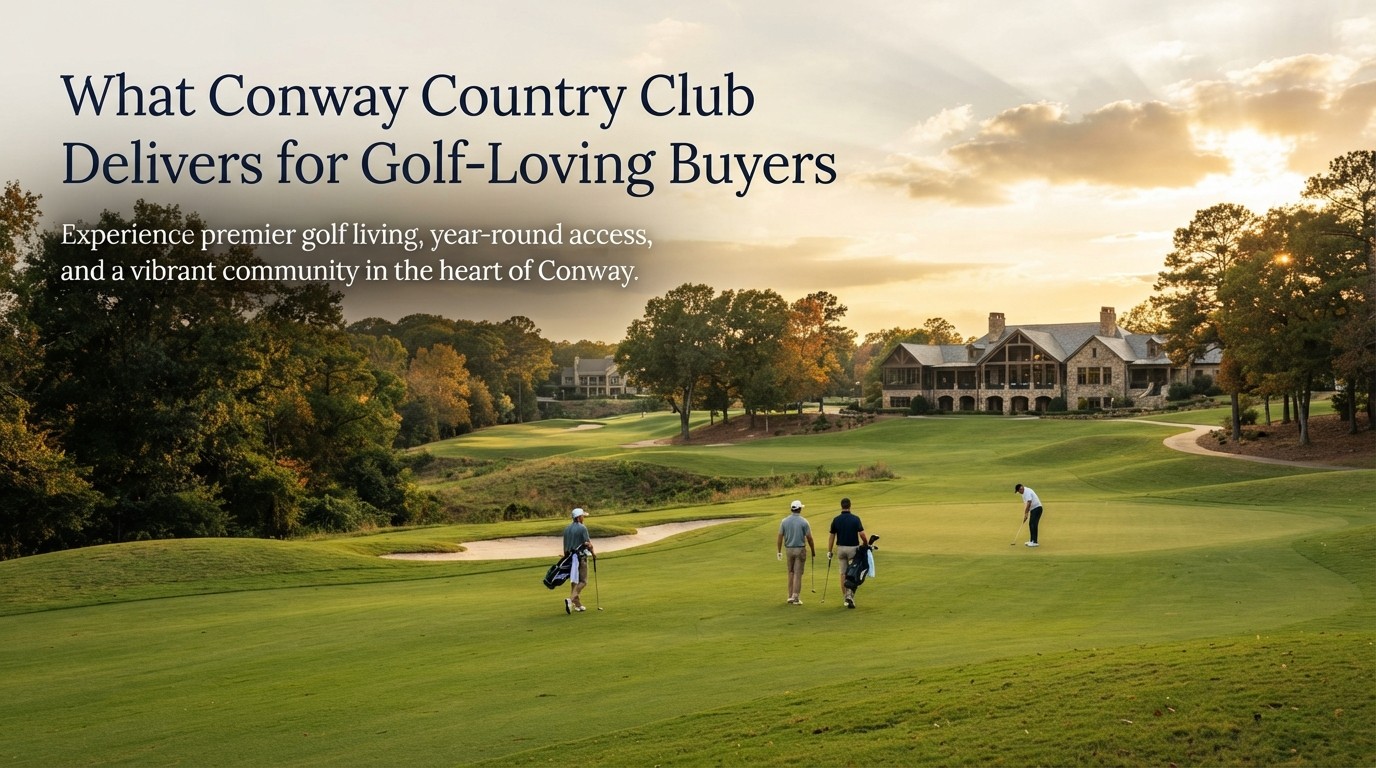
What Conway Country Club Delivers for Golf-Loving Buyers

You golf regularly and want a home that puts the course at the front of your daily life. On the Grand Strand there are only a few communities that actually deliver on that promise, and Conway Country Club is one of them. Here's the honest picture. It's not the flashiest golf community on the strand. It's not the largest. What it is, is one of the more established, quietly consistent golf-adjacent neighborhoods in the Conway market — and for the right buyer, that's exactly the point.

Why Conway Country Club Matters in This Market

The Grand Strand has dozens of golf courses. That doesn't mean every course-adjacent community is a good place to live. What separates a solid golf community from a marketing brochure is course stability, home quality, community identity, and the specific fit between the amenity and the residents.

Conway Country Club has held up in ways some other Grand Strand golf communities haven't. The course has stayed operating. The neighborhood identity has stayed intact. The homes have been maintained and updated by owners who genuinely wanted to live there rather than by flippers looking for a quick turn.
What Conway Country Club Delivers for Golf-Loving Buyers

Who Actually Buys Here

The Conway Country Club buyer pool has a few consistent patterns.

Retirees who golf regularly and want the course as their daily amenity, not a once-a-month feature. Living on or near the course means the golf lifestyle is embedded in daily life.

Snowbirds who spend fall through spring in Conway and want the golf-community setup that makes their winter months easy. Lock-and-leave friendly, active community, and a course they can actually play.

Full-time residents who value the established neighborhood feel and don't want the resort intensity of some larger golf communities further south.

Move-up buyers from other Conway pockets who want a lifestyle upgrade tied to the golf they already play.

What Makes the Community Actually Work

A few specific features that come up in almost every conversation with residents.

Established landscaping and mature trees. The community has been around long enough to feel like a real neighborhood, not a raw new subdivision.

Real course access. Homes here aren't just theoretically near the course — you can walk or drive a cart to the tee.

Manageable community scale. Small enough that neighbors know each other, big enough to have real community events and social structure.

A quieter version of coastal SC. You're 15-20 minutes from Myrtle Beach and 25 minutes from the actual ocean. Enough proximity to hit the beach when you want. Enough distance that daily life happens in a residential neighborhood rather than a tourist corridor.

What Golf-Focused Buyers Should Verify

Standard golf community due diligence applies here too.

The specific club membership structure. Some Grand Strand golf communities require mandatory club dues for all residents. Others make membership optional. Ask exactly what's required and what's optional at Conway Country Club before signing anything.

Course ownership stability. Ask about who owns the course, how the finances look, and whether there are any pending ownership changes. Course closures happen on the Grand Strand and they crush home values in the surrounding neighborhoods.

HOA reserves. Established communities can face capital projects — clubhouse updates, road resurfacing, pool renovation. A healthy reserve position means these projects don't hit you as special assessments.

Play volume. If the course is being played, it's staying profitable. If it's empty on weekends, that's a sign to ask harder questions.

For broader inventory across Conway's golf-oriented options, browse Conway golf course homes alongside Conway Country Club to see how the market looks in your price range.

The Golf Cart Question That Matters

Not every Conway neighborhood is golf cart friendly. Some are. Some aren't. If you plan to use a golf cart around your neighborhood — not just on the course — check the specific rules before you commit. Golf cart friendly neighborhoods in Conway lists the specific communities that support the golf cart lifestyle beyond just course access. Conway Country Club has the pieces that support this kind of daily use, but confirm the specifics for your particular street.

What Conway Country Club Homes Look Like

The inventory here isn't cookie-cutter. Homes range from established mid-tier options that have been owned by the same family for years to updated properties refreshed for modern buyers to occasional luxury builds. If you're looking at the higher end of the Conway market, Conway luxury homes often includes properties in this pocket, alongside other high-end Conway options.

What consistently sells fastest here: well-maintained homes with course frontage or short-walk-to-tee access, updated kitchens, first-floor primaries, and outdoor space that leverages the course view.

What Golf Community Buyers Underestimate

Two patterns worth flagging.

The maintenance load on golf-adjacent homes. Mature landscaping needs care. Windows in course-facing homes get more attention. Balls hit windows, sprinklers overspray, and cart paths need occasional adjacent maintenance. Budget for these realities.

Club dues if applicable. If the community includes required club membership, factor that into your total monthly carrying cost. It can add meaningfully to what your monthly ownership actually costs.

Two Things I Tell Every Conway Country Club Buyer

First, play the course before you buy. Sounds simple. Almost no buyers do it. Renting a cart and playing 18 tells you more about the course quality, the resident engagement, and whether the amenity you're paying for actually matches what you want than any marketing tour ever will. Play first.

Second, talk to a current resident about their annual budget. HOA dues, club fees, cart fees, and incidental charges add up in ways brochures don't fully capture. Fifteen minutes with a neighbor gives you the real number, and the real number often changes how you underwrite the purchase.

Key Takeaways

  • Conway Country Club is one of the more established, consistent golf communities on the Grand Strand — quieter than resort-scale alternatives but reliably solid
  • The buyer pool includes retirees, snowbirds, full-time residents, and move-up golfers from other Conway pockets
  • Established landscaping, real course access, manageable community scale, and quieter coastal SC positioning are the specific value drivers
  • Verify club membership structure, course ownership stability, HOA reserves, and play volume before committing
  • Conway Country Club supports golf cart use for buyers who want that lifestyle beyond just course access
  • The inventory ranges from established mid-tier homes to occasional luxury builds; well-maintained properties with course frontage sell fastest
  • Budget for golf-adjacent home maintenance and any required club dues in your total carrying cost
  • Play the course before you buy and talk to a current resident about their real annual budget

About Greg Harrelson

Greg Harrelson is a seasoned Realtor® with more than 30 years of experience serving the Myrtle Beach and Grand Strand markets. As the founder of Century 21 The Harrelson Group, Greg has built his career helping buyers, sellers, and investors achieve success in every corner of the coastal Carolina real estate market. His expertise spans residential homes, investment properties, land development, and coastal condos. Known for his deep local knowledge, innovative marketing strategies, and commitment to personal service, Greg consistently helps clients reach their real estate goals while navigating the ever-changing market with confidence and precision.
Posted in For Buyers, Lifestyle
Sept. 4, 2026

Move-Up Neighborhoods in Conway for Growing Families

You outgrew your first Conway home about a year ago and now you're seriously shopping the next one. Here's the truth. Conway has a specific band of move-up neighborhoods that consistently work for families in your position — more space, better lot, real character, and prices that still make sense. Communities like Bucksville Oaks come up in almost every conversation I have with growing families. Let me walk you through the neighborhoods where move-up buyers actually land and why each one fits a specific kind of family.

What Move-Up Actually Means for Conway Families

Move-up doesn't just mean bigger square footage. For most families I work with it means: more bedrooms for growing kids, a real yard the whole family can use, a school zone the family wants, a home office or two, and enough storage that the garage isn't full of boxes six months after moving in.

The move-up buyer usually has equity from a starter home to bring to closing. That equity opens options that don't work at the first-time buyer level. It also raises the bar on what buyers expect from the next home.

Bucksville Oaks for Established Family Character

Bucksville Oaks delivers what a lot of Conway move-up families want. Mature trees. Established landscaping. Homes that have been lived in and maintained. The neighborhood has settled into itself — the character is real and can't be manufactured in a newer subdivision. Buyers who want a family neighborhood with soul rather than the anonymous feel of some newer builds consistently land here.

Midtown Village for Modern Family Layouts

Not every move-up family wants an older home. Plenty want newer construction with contemporary floor plans that match how modern families actually live. Midtown Village hits that need. First-floor primary suites, real home offices, updated kitchens, and layouts that flow instead of chopping the house into disconnected rooms. Move-up families relocating from the Northeast or Midwest often gravitate here because the homes match what they had in their previous market at a friendlier price.

Beach Gardens for Established Neighborhood with Room

Beach Gardens sits in a settled Conway pocket with real neighborhood identity. Move-up families who value being able to walk to a friend's house down the street, who want their kids to play in yards visible from the porch, and who prioritize community over the newest amenities often thrive here. The homes range from solid mid-tier options to larger properties for families ready for a real step up.

Briarfield for Space and Privacy

Briarfield attracts move-up buyers who want more separation from neighbors than tight subdivisions provide. Larger lots, more privacy, and homes with the kind of setback that makes the property feel like your own space. If you're moving up specifically to get away from a fence-line neighbor situation, this is where a lot of families land.

 Move-Up Neighborhoods in Conway SC for Growing Families

The 4-Bedroom Sweet Spot Near Conway Elementary

For families whose kids are or will be in the Conway Elementary attendance zone, the four-bedroom inventory near the school is worth focused attention. I keep a running list of 4-bedroom homes near Conway Elementary School because so many move-up families want that specific combination — enough bedrooms for growing family plus the specific school zone. When the right property comes up in this niche, it typically doesn't sit long.

Historic Conway for Character-Focused Families

Some move-up families don't want a newer subdivision at all. They want the character, sidewalks, and community of the historic downtown Conway district. Homes there range from character cottages that need attention to fully renovated period homes with modern systems. Families who choose this route usually value walkable neighborhoods over larger yards and accept that historic homes come with a real maintenance load.

What Move-Up Families Should Actually Prioritize

A few things I push every move-up buyer to think through before falling in love with a specific home.

The school attendance zone by exact street address. Community names don't always match zones. Confirm through Horry County Schools before writing the offer.

The specific bedrooms your growing family will need in five and ten years, not just today. Kids get bigger. They want their own space. The extra bedroom or the flex room becomes more valuable over time.

Home office space if either parent works from home. The move-up home should support how the family actually lives, not just how they lived in the starter.

Outdoor space that fits the family's actual outdoor life. Trampolines, pools, gardens, dog runs, playhouses — the yard should support how your kids will actually use it.

The realistic commute at rush hour. Not the GPS estimate. The actual timing during the school year.

What Move-Up Families Underestimate

Two patterns I watch consistently.

The cost of scaling up. Bigger home means bigger utility bills, more furniture to buy, more square footage to maintain, and often more HOA responsibilities. Move-up families sometimes budget for the mortgage payment but not for the fuller carrying cost.

The emotional attachment to the starter home. Selling the first home is often harder than families expect. Build in some time to process that transition rather than rushing straight from closing to move-in.

For broader Conway market context alongside these specific neighborhoods, browsing Conway real estate inventory helps families see what's on the market at their target price point.

Two Things I Tell Every Move-Up Family in Conway

First, sell before you buy if you can. Move-up families who try to buy first and sell later often end up stretched thin financially and stressed by two simultaneous transactions. The families who sell first, live in temporary housing for a few weeks, and then buy calmly consistently make better decisions and end up in better homes.

Second, don't skip the pre-listing prep on your current home to save time. The proceeds from your starter home directly fund your move-up. Sellers who invest in prep and marketing on the starter typically walk away with more equity to bring to the next purchase. That equity difference can be the gap between the home you want and the home you settle for.

Key Takeaways

Conway offers a specific band of move-up neighborhoods that consistently work for growing families. Bucksville Oaks delivers established character with mature landscaping for buyers who want neighborhood soul. Midtown Village provides newer construction with modern family layouts and floor plans that match how families actually live today. Beach Gardens combines settled neighborhood identity with real yard space. Briarfield attracts families wanting privacy and separation from tight subdivision feel. The 4-bedroom inventory near Conway Elementary is a specific niche worth focused attention for families in that attendance zone. Historic downtown Conway serves families who prioritize character and walkability over larger yards. The move-up decisions that consistently work involve verifying school zones by exact address, prioritizing homes that fit five-to-ten-year family needs rather than just today's, and building in real outdoor space and home office capacity. Selling the starter home before buying the move-up, and investing in real pre-listing prep on the starter, are the two seller-side decisions that most directly determine how much equity families bring to the next purchase — and how happily they land in it.

About Greg Harrelson

Greg Harrelson is a seasoned Realtor® with more than 30 years of experience serving the Myrtle Beach and Grand Strand markets. As the founder of Century 21 The Harrelson Group, Greg has built his career helping buyers, sellers, and investors achieve success in every corner of the coastal Carolina real estate market. His expertise spans residential homes, investment properties, land development, and coastal condos. Known for his deep local knowledge, innovative marketing strategies, and commitment to personal service, Greg consistently helps clients reach their real estate goals while navigating the ever-changing market with confidence and precision.
Sept. 3, 2026

Neighborhoods Near Coastal Carolina University Worth a Look

You're shopping for a home within a reasonable drive of Coastal Carolina University and the standard advice keeps pointing you at the same handful of subdivisions. Let me expand your list. The CCU-adjacent map has more good options than most buyers realize, and a few pockets — like Aquila Estates — quietly work better than the marketing suggests. Whether you're a parent buying for a student, a faculty member looking for a short commute, or an alumnus who wants to stay close to the school after graduating, here's what to actually consider.

Why CCU Shapes the Housing Map

CCU sits off Highway 544 on the south side of Conway. That single location shapes a lot of the housing decisions buyers make around it. The corridors between the campus and Highway 501 attract buyers who want a quick drive to class or the office. The corridors north of the university appeal to full-time residents who value CCU's presence without living directly in it. Understanding the geography helps you know which neighborhood actually fits your daily rhythm.

Aquila Estates for Newer Construction Close to Campus

Aquila Estates delivers a specific value proposition — newer construction within short driving distance of CCU, at price points that keep the mortgage math reasonable for parent buyers and younger faculty. What buyers respond to here: modern layouts, real home offices, first-floor primary suites in many builds, and predictable HOA amenities. If you want a house that's already set up for how people actually live in 2026, this is one of the better options.

Pecan Grove for Established Neighborhood Feel

Not every buyer wants brand-new construction. Some want mature trees, established landscaping, and a neighborhood that's been settled long enough to feel like a real place. Pecan Grove hits that specific note. Homes here have been lived in, updated, and cared for by multiple owners. The community identity is real. For faculty and alumni buyers who value neighborhood over new, this is worth a serious look.

Pottery Landing for Waterway Access and Character

Here's a pocket most CCU-area buyers don't fully consider. Pottery Landing combines proximity to the university with real character that newer subdivisions can't match. The homes are distinctive. The lots have depth. Buyers who prioritize the specific home over the specific community often end up here after touring the more marketed options and realizing they wanted something more.

Condos for Students, Downsizers, or Investors

Not everyone wants a house. Conway condos for sale serve several CCU-related buyer types. Parents buying for students who'll live there four years and either sell or hold as a rental afterward. Downsizing retirees who want a lock-and-leave setup. Investors looking for rental income tied to the university's student and faculty population. Each has a different sweet spot within the condo inventory. Parents typically want durable, simple layouts. Retirees want amenity access and predictable HOA. Investors want the specific units with strong rental history.

Conway Country Club and Golf-Adjacent Living

For buyers who golf regularly and want to live near CCU, the Conway Country Club corridor delivers something specific. Golf access, established community feel, and location that still puts you within reasonable range of the university. Faculty golfers, retired alumni, and buyers who want a lifestyle amenity beyond just a house often land here.

The Historic Conway Downtown Option

Don't rule out the historic district. It's a 10-15 minute drive from the university, close enough that faculty and staff can live there comfortably, and the neighborhood character is something you can't manufacture in a modern subdivision. Walk to Main Street. Bike to the Riverwalk. Live in a real downtown instead of a suburban approximation of one. For CCU-adjacent buyers who value walkable neighborhood over parking-lot proximity, this is a real option that gets overlooked because it's not immediately next to campus.

 Neighborhoods Near Coastal Carolina University Worth a Look

What CCU-Area Buyers Should Verify

Standard due diligence with a few CCU-specific twists.

Rental rules in the specific community. If you're a parent buying with the intent to rent the property after graduation, or an investor buying for student rentals, verify the HOA and municipal rules before writing an offer. Some communities allow rentals freely. Others have caps or restrictions that limit your options.

Commute to campus at the specific time you'll actually make the drive. Highway 544 traffic on game weekends, academic drop-off, and daily commute hours can vary meaningfully.

Internet by exact address if you have students or remote workers who need reliable connections.

Insurance quotes. Coastal SC insurance realities apply even inland, and the layered coverage still matters.

School attendance zones if you're a family buyer with school-age children. Community names don't always match school zones.

What CCU-Area Buyers Underestimate

Two things I watch play out consistently.

Game weekend impact. Home football and baseball weekends genuinely change the neighborhood dynamics near campus. Streets close. Traffic backs up. Parking gets creative. Some buyers love the energy. Others find it more disruptive than they expected.

The rental cycle if you're using the property that way. Student leases run with the academic calendar. If you close on a rental property in November, you may sit empty until August. Build that into your underwriting.

Two Things I Tell Every CCU-Area Buyer

First, visit the neighborhood at academic hours and at game hours before committing. Tour on a Tuesday morning during a school week and a Saturday morning during a home game. The two experiences tell you different things about how the neighborhood actually functions. Buyers who see both make much better decisions than buyers who only visit once.

Second, if you're a parent-buyer using this as student housing, don't underestimate the maintenance. Student-occupied homes wear faster than owner-occupied. Floors take more abuse. Appliances break more often. Build a higher maintenance reserve into your ownership numbers.

Key Takeaways

  • CCU-adjacent housing offers more good options than the standard marketed list suggests
  • Aquila Estates delivers newer construction close to campus at family-friendly price points
  • Pecan Grove provides established neighborhood feel with mature landscaping for buyers who value community over new
  • Pottery Landing offers distinctive character and Waterway-adjacent lots for buyers who want something beyond typical subdivision inventory
  • Conway condos serve parent buyers, downsizers, and investors with different sweet spots by unit type
  • Conway Country Club delivers golf-adjacent living for buyers who want a lifestyle amenity beyond the house itself
  • The historic Conway downtown is a genuinely walkable option 10-15 minutes from campus that gets overlooked
  • Verify rental rules, actual commute time, internet, insurance, and school zones by exact address before writing an offer
  • Game weekends and student-tenant maintenance loads are the two items CCU-area buyers most often underestimate

About Greg Harrelson

Greg Harrelson is a seasoned Realtor® with more than 30 years of experience serving the Myrtle Beach and Grand Strand markets. As the founder of Century 21 The Harrelson Group, Greg has built his career helping buyers, sellers, and investors achieve success in every corner of the coastal Carolina real estate market. His expertise spans residential homes, investment properties, land development, and coastal condos. Known for his deep local knowledge, innovative marketing strategies, and commitment to personal service, Greg consistently helps clients reach their real estate goals while navigating the ever-changing market with confidence and precision.

Posted in For Buyers, Lifestyle
Sept. 2, 2026

The Best Luxury Areas in North Myrtle Beach

You're shopping for a luxury home in North Myrtle Beach and want to know which specific pockets actually deliver the experience the marketing promises. Here's the answer. Luxury in NMB doesn't concentrate in one neighborhood — it shows up across a few distinct areas that each serve a different kind of luxury buyer. Whether you want oceanfront presence, gated golf community amenities, or waterfront estate character, North Myrtle Beach real estate has the specific pocket that fits. Let me walk you through where the actual luxury lives.

What Luxury Actually Means in This Market

Before diving into the areas, here's how luxury actually gets defined on the north end of the Grand Strand. Ocean proximity, lot size, home quality, community amenity access, and privacy all factor in. A luxury home in NMB typically means direct or near-direct ocean access with substantial square footage, or a large lot in a gated community with resort-level amenities, or a waterfront property with real dock capabilities. Prices at the true luxury tier commonly run well past a million dollars, with the ceiling reaching several million for the top oceanfront estates.

Cherry Grove Oceanfront and Canal-Front

The Cherry Grove north end delivers some of the most distinctive luxury inventory in the entire NMB market. Two categories dominate.

Oceanfront raised beach homes. Direct sand access, elevated construction with parking underneath, expansive decks, real square footage. These homes command premium pricing but deliver the classic Grand Strand oceanfront lifestyle.

Canal-front homes. The canal network unique to Cherry Grove supports luxury inventory with private docks, boat access, and quieter water frontage than the direct ocean. Buyers who value boating over crashing surf often prefer canal homes to comparable oceanfront properties.

What distinguishes Cherry Grove at the luxury tier: real neighborhood character alongside the vacation rental market. Some blocks are heavily rented. Others are predominantly owner-occupied. If you're buying at the luxury tier for full-time or serious second-home use, verify the block's rental density before committing.

Ocean Drive Beach-Block

Ocean Drive's tight residential grid with beach-block proximity delivers a specific luxury experience — walkable to Main Street restaurants, walkable to the sand, real neighborhood identity that vacation-only properties can't replicate.

Luxury inventory here tends to include custom-built homes on lots that have been in family hands for decades. When these properties come to market, they don't stay long. Buyers who want the Ocean Drive lifestyle at the luxury tier often wait months or years for the specific property they want.

Barefoot Resort

Barefoot Resort on the inland side of NMB represents a different luxury proposition. Gated golf community with multiple courses, resort-level amenities, marina access to the Intracoastal Waterway, and a mix of custom single-family homes, high-end condos, and townhomes.

What Barefoot delivers: comprehensive amenity access without the maintenance load of direct beach ownership. The trade-off is 10-15 minutes to the actual sand instead of walking distance.

Barefoot works especially well for buyers who prioritize golf, community amenity depth, and predictable HOA-managed exterior maintenance. Buyers who want to walk to the beach every morning will feel the inland location.

Tidewater Plantation

Tidewater sits on a peninsula between the Intracoastal Waterway and the marsh, delivering a distinctive geographic setting most NMB inventory doesn't match. Golf course, gated community, custom homes, and a private beach club at the ocean provide amenity access that stitches inland community life with real ocean use.

The buyer profile at Tidewater skews toward full-time residents and serious second-home owners. Not a resort community with rentals dominating — a real residential community with amenity depth.

The Best Luxury Areas in North Myrtle Beach     Crescent Beach Custom Homes

Crescent Beach doesn't get marketing attention as luxury inventory, but the reality on the ground is that some of the most impressive custom homes in NMB sit in Crescent Beach's quieter blocks. Newer construction, generous lots by beach-block standards, and the calmest of the four NMB beach pockets deliver a specific luxury feel — less resort energy, more residential character.

For buyers who want luxury quiet rather than luxury visibility, Crescent Beach is under-appreciated.

Intracoastal Waterway Waterfront

Various pockets along the Intracoastal Waterway in NMB support luxury waterfront homes with private docks, boat lifts, and direct water access. These properties command real premiums but deliver a lifestyle that neither pure oceanfront nor golf-community options match.

Serious boaters at the luxury tier often prioritize ICW waterfront over oceanfront specifically because of the daily water use. You can run out to the ocean through the Little River inlet, but you can also cruise the ICW for miles without leaving protected water.

What Luxury Buyers Should Verify Anyway

Even at the luxury tier, standard due diligence still applies — sometimes with higher stakes.

Insurance quotes. Coastal luxury insurance runs meaningfully higher than mid-tier inventory. Get the real numbers during inspection.

Flood zone status and elevation certificate.

Dock and slip permits if the property has water access. What conveys, what's transferable, what would require reapplication.

HOA reserves and any pending special assessments in gated communities.

Home condition — luxury doesn't mean flawless. Custom homes have their own quirks, particularly at older builds.

Property tax at the 4 percent primary residence rate versus 6 percent for second homes. On luxury inventory, the difference is meaningful.

What Luxury Buyers Underestimate

A few patterns I've watched at the luxury tier.

Coastal insurance can genuinely change the affordability picture. Buyers who don't underwrite this before contract sometimes get surprised at the layered cost.

Custom home maintenance at the coast is real work. Specialized systems, higher-quality materials that still wear from salt air, more square footage to maintain — luxury coastal ownership isn't turnkey.

Rental restrictions vary widely at the luxury tier. Some communities allow short-term rentals freely. Others don't. If income offset is part of your plan, verify before contract.

Two Things I Tell Every Luxury NMB Buyer

First, tour multiple pockets before committing to one. Oceanfront Cherry Grove feels genuinely different from gated Tidewater which feels different from walkable Ocean Drive. Luxury buyers who commit before seeing the alternatives sometimes wish they'd known other options existed. Give yourself the education before writing the offer.

Second, plan for total carrying cost at the luxury tier, not just the mortgage. Insurance, taxes, HOA dues where applicable, maintenance budget, dock or slip fees. On a multi-million dollar coastal home, total annual carrying cost commonly runs into six figures. Better to know the number before you commit than to be surprised after closing.

Key Takeaways

Luxury in North Myrtle Beach shows up across several distinct pockets that each serve a different luxury buyer profile. Cherry Grove oceanfront and canal-front delivers vacation-classic Grand Strand lifestyle with the option of boat access. Ocean Drive beach-block combines walkability, neighborhood identity, and beach proximity with limited inventory turnover. Barefoot Resort delivers gated golf community amenity depth at the inland trade-off. Tidewater Plantation stitches inland community with private beach club access. Crescent Beach's custom homes offer luxury quiet for buyers who prefer residential character over resort energy. Intracoastal Waterway waterfront serves serious boaters who prioritize daily water use. Standard due diligence — insurance, flood, dock permits, HOA reserves, home condition, property tax structure — matters even more at the luxury tier because the stakes are higher. Custom coastal maintenance, insurance cost realities, and community rental restrictions are the three items luxury buyers most often underestimate. Touring multiple pockets before committing and modeling total annual carrying cost are the two decisions that consistently lead luxury buyers to homes they own happily for years.

About Greg Harrelson

Greg Harrelson is a seasoned Realtor® with more than 30 years of experience serving the Myrtle Beach and Grand Strand markets. As the founder of Century 21 The Harrelson Group, Greg has built his career helping buyers, sellers, and investors achieve success in every corner of the coastal Carolina real estate market. His expertise spans residential homes, investment properties, land development, and coastal condos. Known for his deep local knowledge, innovative marketing strategies, and commitment to personal service, Greg consistently helps clients reach their real estate goals while navigating the ever-changing market with confidence and precision.

Posted in For Buyers, Lifestyle
Sept. 1, 2026

What to Look for in HOA Documents Before You Close

You're under contract on a condo, townhome, or subdivision home along the Grand Strand and your closing attorney just handed you a thick stack of HOA documents. Most buyers glance at them, sign the receipt, and move on. That's a mistake. The information in that stack is where post-closing surprises get hidden, and reviewing it carefully is the single most important due-diligence step for anyone buying into an HOA-governed community. Whether you're shopping Myrtle Beach real estate condos or a Conway subdivision home, here's what you actually need to look for.

What's Usually in the HOA Document Package

A typical HOA disclosure package includes bylaws, the declaration of covenants (CC&Rs), rules and regulations, the current budget, the most recent financial statements, meeting minutes from the last one to two years, the most recent reserve study, and current dues and assessment schedules.

Some of these are boring. Some contain the specific information that determines whether your ownership goes smoothly or turns painful. Knowing which sections matter most is the difference between an informed buyer and a surprised owner.

The Reserve Study Is the Most Important Document

Here's the thing. The reserve study projects the HOA's capital needs over the next 20-30 years and shows how well-funded the reserves actually are relative to those needs.

What you're looking for. A reserve study that shows the HOA is at or near 100 percent funded means the community has money set aside for major repairs and replacements. A study that shows the HOA is at 50 percent funded or less means special assessments are likely coming — sometimes soon, sometimes over a decade, but coming.

Older coastal condo buildings frequently have underfunded reserves. That's the single most common trigger for special assessments in this market. If your target property is in a building with a weak reserve position, you should either negotiate the price accordingly or expect assessments in the future.

Meeting Minutes Reveal What's Actually Happening

The last one to two years of HOA meeting minutes tell you what the community is actually dealing with. Pending projects. Discussions about future assessments. Disputes between owners. Board dynamics. Insurance issues. Maintenance concerns.

What to specifically look for in the minutes:

Any discussion of upcoming capital projects — roof, elevator, dock, paint, pool, HVAC systems.

Mentions of insurance renewals or claims. Coastal properties can face insurance challenges that affect assessments.

Legal proceedings or disputes. A community in active litigation is often not a great community to buy into.

Board turnover or governance issues. Frequent board changes suggest instability.

Owner complaints and how they're handled. Reflects the community culture.

What to Look for in HOA Documents Before You Close

The Financial Statements Beyond the Reserves

Beyond the reserve position, the current financial statements reveal how the HOA operates day to day.

Operating budget: is the HOA running at a surplus, breaking even, or losing money each year? Communities that operate at a loss typically address it through dues increases or assessments.

Delinquencies: how many owners are behind on their dues? High delinquency rates mean the community's finances are on thinner ice than the numbers suggest.

Insurance costs as a percentage of the budget: rapidly rising insurance costs (a real issue on coastal SC properties) can drive dues increases even in otherwise healthy HOAs.

The Rules That Matter Most

Most buyers skim the CC&Rs. That's a mistake because these documents contain the specific rules that will govern how you can use your property.

Rental rules. Can you rent long-term? Short-term? Are there caps on the total number of rentals? Minimum lease terms? Approval requirements for tenants? If you might rent the property at some point, this matters.

Pet restrictions. Weight limits, breed restrictions, number of pets. Some communities are strict about this.

Exterior modifications. Can you change paint colors, add a fence, install a satellite dish, plant landscaping, add a screened porch? Some HOAs require approval for almost every visible change.

Parking rules. Assigned spots, visitor parking, RV or boat storage, work vehicles.

Age restrictions. Some communities are 55+ or have age-related rules that limit who can live there.

The Assessment History That Predicts the Future

Ask specifically for the assessment history over the last five to ten years. This tells you the pattern.

Communities that have never assessed usually have strong reserves — or they haven't hit a major capital need yet.

Communities with a recent assessment usually addressed the immediate need but might be behind on the next one.

Communities with multiple recent assessments have a pattern of underfunding. Expect more.

Combine assessment history with the reserve study to get a real picture of what's likely coming.

Master Insurance Policy Details

For condo buildings and some planned communities, the master insurance policy covers building exteriors, common areas, and sometimes basic interior finishes. What you need to know:

What the master policy covers versus what your owner policy (typically an HO-6) covers. The gap between them is where owners get surprised.

Wind and hail coverage — is it in the master policy, or does the HOA require owners to carry it separately?

Flood coverage — same question. For coastal properties this matters.

Deductibles — what would owners face if there's a claim? Some master policies have percentage-based deductibles that surprise owners after storms.

Financing Restrictions Nobody Warns You About

Some HOA-governed properties don't qualify for conventional financing because of specific HOA characteristics. What can trigger this:

Owner-occupancy ratio below lender thresholds (typically 50 percent for many conventional loans).

Litigation involving the HOA.

Underfunded reserves below lender standards.

Concentration of ownership by a single owner or entity.

Excessive commercial space in a mixed-use building.

Ask your lender to review the HOA documents before you commit if there's any doubt about financing.

For broader context on how these dynamics play out across the region, browse North Myrtle Beach real estate and Conway real estate inventory to see how different community types are pricing and performing.

Two Things I Tell Every Buyer Reviewing HOA Docs

First, read the last two years of meeting minutes cover to cover. This is where the community's real story lives. If you only have time for one HOA document, this is the one. Meeting minutes tell you what's actually being discussed, what problems exist, and how the board handles them.

Second, don't be afraid to walk away from a bad HOA situation. Underfunded reserves, active litigation, high delinquency, or rules that don't match your intended use are all legitimate reasons to end a deal during the inspection period. Better to lose the earnest money conversation now than to be stuck with a special assessment and a home you can't easily sell later.

Key Takeaways

The HOA disclosure package is where post-closing surprises get hidden, and reviewing it carefully is the single most important due-diligence step for anyone buying into an HOA-governed community along the Grand Strand. The reserve study reveals whether special assessments are likely coming. Meeting minutes tell you what the community is actually dealing with day to day. Financial statements show delinquencies, operating patterns, and insurance cost pressure. The CC&Rs and rules dictate how you can actually use your property. Assessment history predicts future assessments. Master insurance policies define where owner coverage begins and ends. Some HOA situations can even prevent conventional financing. Buyers who invest a few hours reading the HOA package carefully consistently avoid the ownership surprises that catch other owners. Buyers who skim these documents often discover the problems the hard way — usually through an unexpected special assessment or a rule that limits how they wanted to use the property. The inspection period is when you have leverage. Use it.

Frequently Asked Questions

How long is the HOA document review period in South Carolina?

The specific window varies by contract, but most SC purchase contracts allow the buyer several days to review HOA documents and terminate if they find issues. The exact window is negotiated in your purchase contract, so verify with your agent when the review deadline actually falls.

What's a reasonable HOA reserve funding percentage?

Industry guidance generally suggests HOAs should aim for 70-100 percent of full funding based on the reserve study's calculations. Communities under 30 percent funded typically have special assessments in their near future. Between 30-70 percent is a gray zone that depends on the specific capital timeline.

Can I negotiate the price if the HOA has issues?

Yes. HOA problems discovered during due diligence — underfunded reserves, upcoming assessments, unfavorable rules — are legitimate negotiation points. Sellers who want the deal to close often adjust when a real HOA concern surfaces. Whether the seller agrees depends on the specific issue and the market.

Are Grand Strand condo HOAs different from subdivision HOAs?

Yes, meaningfully. Condo HOAs typically manage building exteriors, elevators, roofs, and common insurance policies — with much bigger capital exposure than subdivision HOAs. Subdivision HOAs mostly handle common areas, pools, and community amenities. Reserve requirements and assessment risk are usually higher in condo HOAs.

Can I contact the HOA directly with questions before closing?

Generally yes, though the specific approach varies. Some HOAs prefer to route questions through the seller or the closing attorney. Others allow direct contact. Ask your agent about the appropriate channel for your specific target property.

About Greg Harrelson

Greg Harrelson is a seasoned Realtor® with more than 30 years of experience serving the Myrtle Beach and Grand Strand markets. As the founder of Century 21 The Harrelson Group, Greg has built his career helping buyers, sellers, and investors achieve success in every corner of the coastal Carolina real estate market. His expertise spans residential homes, investment properties, land development, and coastal condos. Known for his deep local knowledge, innovative marketing strategies, and commitment to personal service, Greg consistently helps clients reach their real estate goals while navigating the ever-changing market with confidence and precision.

Aug. 31, 2026

Why Dillon Is Gaining Attention From Homebuyers

You've been shopping the Grand Strand and hitting price ceilings that don't work for your budget. A few buyers I've worked with recently have started asking about Dillon. Here's the honest answer. Dillon sits about an hour west of Conway in Dillon County, and it delivers the deepest value in the entire region for buyers who can accept the drive. It's not for everyone. But for the specific buyer who fits, Dillon is genuinely one of the most under-appreciated places to buy right now — and worth understanding alongside broader options like Conway real estate when you're mapping your budget against your priorities.

Where Dillon Actually Sits

Dillon is the county seat of Dillon County. Roughly an hour drive from Conway, an hour and a half from Myrtle Beach, and just south of the North Carolina line. Population around 6,500 in the town proper. I-95 runs right past Dillon, which shapes some of the local character — think highway travelers, South of the Border tourism, and a working town identity that predates the Grand Strand's growth.

What surprises visiting buyers: Dillon has real historic character, a downtown that's held onto itself, and a rural pace that feels genuinely different from anywhere along the coast.

Why Dillon Is Gaining Attention Right Now

Several shifts have moved Dillon onto more buyers' radars.

Remote work permanence. Buyers who don't commute daily are willing to live further from major amenities. Dillon delivers real space for buyers whose daily life is at home.

Grand Strand price increases. Buyers priced out of Conway and Longs have started looking further inland. Dillon is the next logical stop for value-focused buyers who don't need immediate coastal proximity.

Housing supply. Dillon has more inventory per buyer than the coast, which means better negotiating position and less bidding pressure.

SC property tax structure. Same 4 percent primary residence assessment ratio applies here as anywhere else in South Carolina, but lower home values mean lower total tax bills.

Cost of living. Groceries, services, general daily costs all run friendlier than closer to the coast.

Who Actually Buys in Dillon

The Dillon buyer pool is specific.

Retirees who did the math and decided their retirement dollars stretch much further in Dillon than in Myrtle Beach. They can own a home outright, keep monthly expenses low, and drive to the coast when they want.

Remote workers who need reliable internet and don't need daily commutes. Dillon's fiber has expanded, though verify by address.

Buyers from the Carolinas who want deep-country living without leaving the state. Charlotte, Charleston, and Raleigh are all drivable weekend trips from Dillon.

Investors buying rental inventory in a market where the numbers still pencil. Small-town rentals to local workforce often produce better cap rates than saturated coastal markets.

Buyers with family ties to the area returning after years away. This is a real segment of the local buyer pool.

Why Dillon Is Gaining Attention From Homebuyers

What Dillon Actually Costs

Realistic price observations. Older single-family homes in town run in a much lower band than anywhere in Horry County. Historic homes with real character are especially attractively priced for what you get. Newer construction is limited but exists. Rural acreage nearby is available at prices that don't exist along the coast.

Dollar for dollar, Dillon delivers more house and more land than any other option most Grand Strand buyers evaluate.

What Dillon Actually Delivers

Beyond the price, here's what makes Dillon work for the right buyer.

Real small-town identity. Dillon isn't a bedroom community. It has its own history, its own downtown, its own community events. That kind of authentic place identity is rare.

Actual privacy. Rural properties around Dillon deliver real distance from neighbors. If quiet matters to you, this is quiet.

I-95 access. Traveling for work, family, or extended trips is meaningfully easier from Dillon than from the Grand Strand corridor. You're on the interstate in minutes.

McLeod Medical Center Dillon provides real local healthcare. Specialists still require driving to Florence or Myrtle Beach, but primary care is covered.

South Carolina character. If you want the South Carolina you imagined — Southern hospitality, slower pace, real community — Dillon delivers that in ways coastal tourist markets can't.

The Trade-Offs You Have to Accept

Dillon isn't for everyone. Here's what you're giving up.

The drive. Coast is 60-90 minutes. Florence is 30 minutes for major shopping and healthcare specialists. Charlotte is over two hours. Any daily life that requires frequent coastal access won't work.

Retail depth. Dillon has functional daily-life retail but nothing like the depth of coastal markets. Specialty shopping requires real drives.

Restaurant variety. Local options exist. Chain and specialty dining requires driving to Florence or beyond.

Cultural amenities. Museums, theaters, cultural institutions are limited locally.

School program depth. Dillon County schools have solid foundations but narrower advanced course options than larger county school systems.

For buyers whose lifestyle depends on any of these being close, Dillon doesn't work. For buyers whose lifestyle mostly happens at home, Dillon delivers.

What Dillon Buyers Should Verify

Standard due diligence still applies.

Well and septic for rural properties. Water testing during inspection is non-negotiable.

Internet quality by exact street address. Fiber has grown but isn't universal.

Flood zone status if you're near any water. Dillon County has areas with real flood exposure.

Property tax status. File for the 4 percent primary residence rate after closing.

Historic district rules if you're buying in downtown Dillon. Preservation guidelines can affect renovation plans.

For broader inventory comparison, browsing Loris real estate alongside Dillon shows where the value gap actually sits between rural Horry County and Dillon County.

Two Things I Tell Every Buyer Considering Dillon

First, drive from Dillon to your realistic daily destinations before you buy. Costco, healthcare, family visits, weekend activities. Time the drives at real hours. If any of those drives feel unmanageable at the frequency you'd actually make them, Dillon doesn't work. If they're all fine, the value math is genuinely compelling.

Second, visit Dillon at multiple times. A Tuesday morning shows you daily life. A Saturday shows you weekend rhythm. A Sunday afternoon shows you how quiet the town gets when it's supposed to be quiet. Buyers who see all three make better decisions than buyers who visit once during a marketing tour.

Key Takeaways

  • Dillon sits about an hour west of Conway with genuinely deep value pricing for buyers who can accept the drive to coastal amenities
  • Remote work, Grand Strand price increases, and cost-of-living math are the main forces putting Dillon on more buyers' radars
  • Buyer types finding value in Dillon include retirees, remote workers, buyers with family ties, investors, and buyers seeking real rural character
  • Dollar for dollar, Dillon delivers more house and more land than any Grand Strand option most buyers evaluate
  • Real small-town identity, I-95 access, McLeod Medical Center Dillon for primary care, and authentic Southern character are the ownership benefits
  • Trade-offs include coast being 60-90 minutes away, limited retail and restaurant depth, narrower school program options, and long drives to specialty services
  • Verify well and septic, internet quality, flood zone status, property tax filing, and historic district rules by exact address
  • Drive your realistic daily destinations before buying and visit at multiple times of day and week before committing

About Greg Harrelson

Greg Harrelson is a seasoned Realtor® with more than 30 years of experience serving the Myrtle Beach and Grand Strand markets. As the founder of Century 21 The Harrelson Group, Greg has built his career helping buyers, sellers, and investors achieve success in every corner of the coastal Carolina real estate market. His expertise spans residential homes, investment properties, land development, and coastal condos. Known for his deep local knowledge, innovative marketing strategies, and commitment to personal service, Greg consistently helps clients reach their real estate goals while navigating the ever-changing market with confidence and precision.

Aug. 28, 2026

Why Buyers Looking for Value Choose Little River

You've priced homes in North Myrtle Beach and hit the ceiling of what your budget allows. Then someone told you to look at Little River real estate and the math suddenly makes sense. Here's why. Little River sits about 15-20 minutes north of North Myrtle Beach via Highway 31, and the pricing on comparable inventory runs meaningfully lower than the beach-adjacent alternatives. That gap is what pulls value-focused buyers up here every day of the week.

What Value Actually Means in This Market

Value doesn't mean cheap. It means you get more house, more land, more amenity, or more water access for the same money than you'd get in a comparable coastal pocket. Little River delivers this in ways that hold up over years of ownership.

A $400,000 budget in North Myrtle Beach might get you an older cottage a few blocks from the ocean. The same $400,000 in Little River can get you a newer 3-bedroom single-family with a garage and a real yard. That's the trade-off in plain terms.

Where the Value Actually Lives

Different pockets of Little River deliver value differently.

Marina communities like Coquina Harbour Condos and Cypress Bay Condos put buyers on the Intracoastal Waterway at entry prices that oceanfront condos can't match. If you value boat access over sand access, this is where the math works best.

Inland single-family in communities like Bridgewater Cottages and various country-club-adjacent developments delivers newer construction on manageable lots at prices below equivalent Carolina Forest or North Myrtle Beach inventory.

Golf-adjacent options like Eastport Golf Homes give you the golf lifestyle at price points meaningfully lower than Grande Dunes or similar coastal golf communities.

Older residential streets in and around downtown Little River offer the most affordable entry into the area, sometimes at prices that surprise buyers from the coast.

The Costs That Also Come Out Lower

Value isn't only about purchase price. Ongoing carrying costs in Little River generally run friendlier than immediate coastal alternatives.

Insurance. Homes further from the ocean typically qualify for lower wind and hail premiums. Flood zone designations vary, but many Little River properties sit in Zone X or lower-risk designations than beach-block properties.

Property tax at the 4 percent primary residence rate applies just like everywhere else in Horry County, but lower home values mean lower total bills.

HOA dues in Little River communities typically run modest compared to amenity-heavy resort communities closer to the coast.

Utility costs are comparable to the rest of the region.

Why Buyers Looking for Value Choose Little River

The Highway 31 Effect Nobody Fully Appreciates

Here's what changed the Little River value proposition over the last decade. Highway 31 cut the drive from Little River to central North Myrtle Beach to about 15-20 minutes. Before that connector was fully utilized, Little River felt like a real drive from the beach. Now it doesn't.

That geographic shift means Little River buyers get real beach access without paying beach-adjacent prices. The commute math works. The lifestyle math works. That's why the buyer pool has broadened so much.

Who Actually Buys for Value in Little River

The value-focused buyer pool splits into a few clear types.

Retirees who priced their retirement home budget carefully and want maximum home per dollar. Little River delivers this consistently.

Second-home buyers from Charlotte, Raleigh, and mid-Atlantic markets who want coastal proximity without oceanfront pricing.

Boaters who understand that a home with marina access delivers more lifestyle per dollar than an ocean-view condo without a slip.

Remote workers who don't need daily beach proximity and want more house for their money.

Investors buying inventory that pencils for long-term rental or moderate short-term rental income.

What Value Buyers Should Verify Anyway

A lower entry price doesn't mean skipping due diligence. Everything you'd verify on a higher-priced coastal home still applies.

Insurance quotes for the specific address, not a general area estimate.

HOA reserves and any pending special assessments if you're buying a condo or an HOA-governed community.

Flood zone status by exact street address.

Home condition — a cheaper home with deferred maintenance issues can end up costing more than a higher-priced well-maintained one.

Boat slip and dock permits if you're buying a marina-community property. What conveys, what's transferable, what would require reapplication.

For broader comparison, browse North Myrtle Beach real estate alongside Little River to see the exact value differences at your target price band.

The Trade-Offs Value Buyers Should Accept

Little River delivers value, but here's what you're accepting in exchange.

Not walking distance to the ocean. The 15-20 minute drive to central North Myrtle Beach is short but real.

Fewer retail and restaurant options than Myrtle Beach proper, though Little River has grown meaningfully in this category over the last several years.

Healthcare specialists sometimes require driving into Myrtle Beach or further.

The tourist economy is more muted than beach-block areas, which some buyers see as a positive and others miss.

Two Things I Tell Every Value Buyer Considering Little River

First, tour comparable inventory in North Myrtle Beach and Little River on the same day. Feel the value difference in real terms — same budget, different homes. Buyers who make this comparison decisively usually pick Little River. Buyers who only tour one area sometimes miss the actual value gap.

Second, be honest about how often you'll actually use the beach. If you'll walk to the sand three times a week, the value math doesn't overcome the daily-life inconvenience. If you'll hit the beach twice a month and value your home most days, Little River delivers real value that keeps compounding over years of ownership.

Key Takeaways

  • Little River sits 15-20 minutes north of North Myrtle Beach via Highway 31, delivering coastal proximity without beach-adjacent pricing
  • Marina communities (Coquina Harbour, Cypress Bay) offer Intracoastal Waterway access at meaningfully lower prices than oceanfront alternatives
  • Inland single-family and golf-adjacent inventory both deliver more home per dollar than equivalent coastal options
  • Ongoing carrying costs — insurance, HOA dues, sometimes flood coverage — often run friendlier than immediate coastal alternatives
  • The Highway 31 connector fundamentally changed the value proposition; the drive to the beach is genuinely short now
  • Value buyer types include retirees, second-home buyers, boaters, remote workers, and investors
  • Standard due diligence still applies — insurance quotes, HOA reserves, flood zones, home condition, dock permits
  • Trade-offs include no walking-distance beach access and slightly narrower retail and healthcare depth
  • Tour comparable inventory in both markets on the same day and be honest about your realistic beach use before committing

About Greg Harrelson

Greg Harrelson is a seasoned Realtor® with more than 30 years of experience serving the Myrtle Beach and Grand Strand markets. As the founder of Century 21 The Harrelson Group, Greg has built his career helping buyers, sellers, and investors achieve success in every corner of the coastal Carolina real estate market. His expertise spans residential homes, investment properties, land development, and coastal condos. Known for his deep local knowledge, innovative marketing strategies, and commitment to personal service, Greg consistently helps clients reach their real estate goals while navigating the ever-changing market with confidence and precision.

Aug. 27, 2026

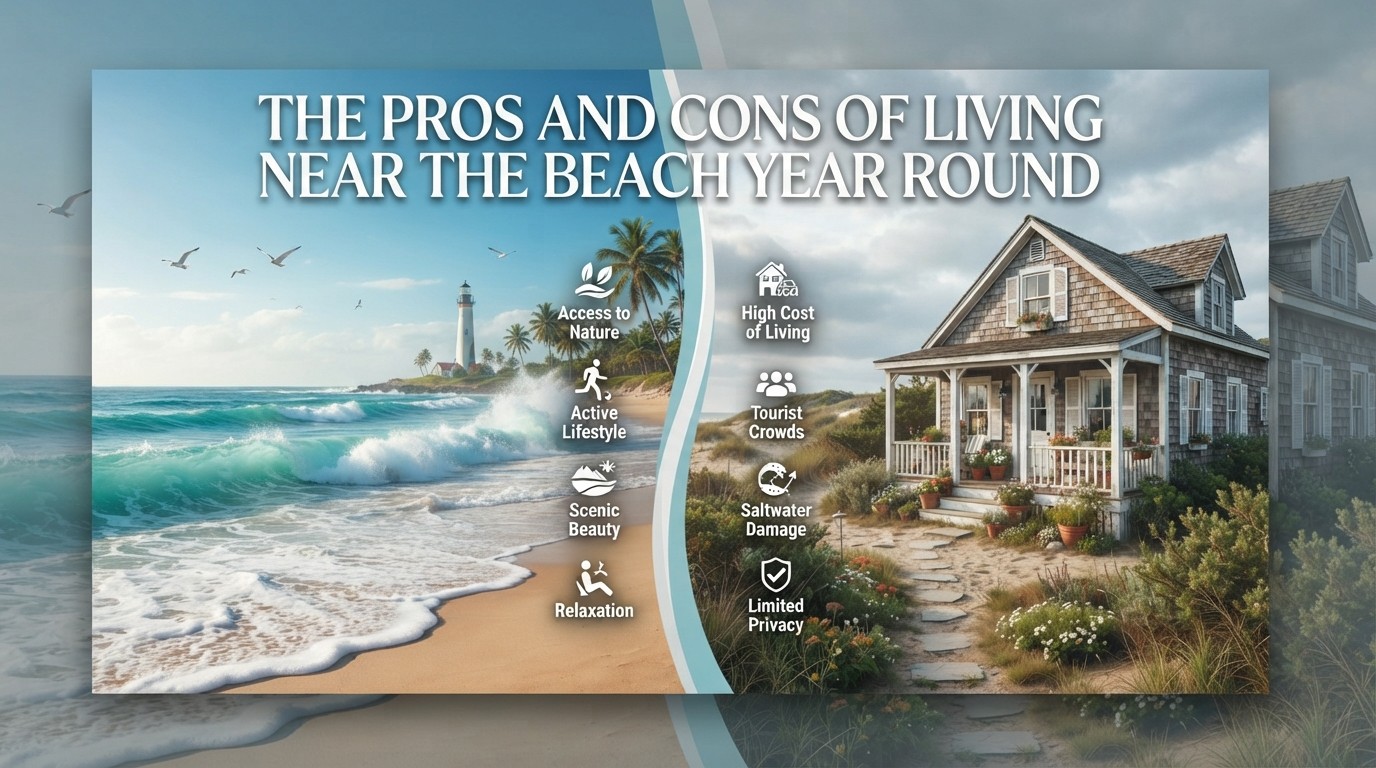
The Pros and Cons of Living Near the Beach Year Round

You've spent enough vacations on the Grand Strand to seriously consider moving down full-time. Before you do, understand this. Living near the beach year round is genuinely different from vacationing near the beach. The pros are real. The cons are also real. Buyers who think through both sides before committing tend to build lives here they love. Buyers who imagine every day is a vacation day often end up frustrated within the first year. Let me walk you through what full-time coastal living actually looks like, whether you're considering Myrtle Beach real estate directly on the sand or something inland.

The Pros That Actually Hold Up

Here's what full-time residents tell me they love, consistently, five and ten years in.

The weather. Grand Strand winters are mild. Snow is rare. You can walk outside in January in a light jacket most days. If you're moving from the Northeast or Midwest, this alone is worth a lot.

The pace. Even in tourist-heavy pockets, the daily rhythm is slower than most cities. Traffic is real in summer but nothing like a major metro. You get more of your day back.

The community. Coastal towns like Cherry Grove, Ocean Drive, and downtown Conway have real neighborhood identities. People know each other. Community events actually happen. That's rarer than it should be in modern America.

The cost of living relative to what you're used to. South Carolina property tax at the 4 percent primary residence rate, combined with generally friendlier grocery and service costs, gives most relocating buyers real financial breathing room compared to origin markets.

The outdoor season. Nine months of usable outdoor weather changes how you live. Screened porches, patios, decks — you'll spend real time outside in ways you can't in colder climates.

The proximity to water. Even inland Grand Strand pockets are 15-30 minutes from the beach. That's a real quality of life feature that never gets old for people who genuinely love the water.

The Cons That Nobody Talks About Enough

Here's what nobody tells you before you move down.

The summer intensity. From June through August the tourist population swells into the millions. Grocery stores are crowded. Restaurants have wait lists. Traffic on Highway 17 Business and Ocean Boulevard becomes brutal. If you live directly in the tourist corridor, you'll feel this every day.

The insurance stack. Coastal SC homes need layered insurance — homeowner's, wind and hail (often through the SC Wind and Hail Underwriting Association), and flood insurance if you're in a designated zone. The combined annual bill runs meaningfully higher than most inland states.

The salt-air maintenance. HVAC units, roofs, exterior hardware, and outdoor equipment all wear faster on the coast. Your maintenance calendar and budget need to reflect that.

Hurricane season anxiety. Every June through November you'll pay attention to weather forecasts differently. Most seasons pass without incident. Some don't. Buyers from inland states usually take a year or two to adjust to living with this.

Healthcare specialists. Primary care and general hospital services are solid at Grand Strand Medical Center, Conway Medical Center, and McLeod. For specific complex care, you sometimes still drive to Charleston or fly to Charlotte.

The off-season quiet. From November through February, tourist areas get noticeably quieter. Some residents love the peace. Others find the shift more isolating than they expected.

Where You Live Changes the Balance

The pros and cons hit differently depending on where you actually land.

Direct beach-block life in Cherry Grove, Ocean Drive, or oceanfront Myrtle Beach delivers the most vacation-like feel and the most tourist intensity in summer. You get the immediate ocean access. You also live in the traffic and noise.

Residential coastal like Market Common or the Pine Lakes/Dunes Club area gives you 5-10 minute beach access with a real residential neighborhood feel most of the year. Good balance for many buyers.

Inland coastal like Conway real estate puts you 15-20 minutes from the ocean with materially lower insurance, more house for the dollar, and a genuine downtown that doesn't shut down after tourist season. Many full-time residents end up here after they realize daily beach access isn't as important as they thought.

Rural-adjacent options in Longs, Aynor, or Loris give you occasional coast access with even friendlier insurance and cost of living. The trade is a real drive to the water.

The Pros and Cons of Living Near the Beach Year Round

What Full-Time Residents Actually Do Differently

Watching hundreds of my clients transition from vacationers to full-timers, here are the patterns of the ones who thrive.

They shop grocery and errands in off-peak hours. Weekdays before 10 a.m. and after 7 p.m. Saturdays after peak tourist departure day. Avoids most of the summer crush.

They use the beach in the shoulder seasons. October, March, April, May — that's when the beach is genuinely at its best. Fewer crowds, better temperatures, more parking.

They build indoor lives too. Book clubs, church communities, hobbies, workshops. Full-time residents who rely only on the beach for entertainment get bored faster than they expect.

They travel out in July and August. Ironically, some of the smartest full-time coastal residents leave during peak tourist season. Visit family up north. Take extended trips. Return in September when the tourists thin out.

They build professional relationships early. HVAC contractor, roofer, insurance agent, doctor. When you need one urgently, having a relationship already established changes everything.

What Vacationers Get Wrong About Full-Time Life

A few honest observations from watching this transition play out.

Vacation weeks are curated experiences. You go to restaurants, hit the beach, do the activities. Full-time life includes the boring parts too. Grocery runs. Doctor appointments. Home maintenance. The beach doesn't fix that.

The vacation excitement fades. Living somewhere feels different than visiting. The first six months are still exciting. By year two, it's just where you live. That's not a bad thing — it's normal. But buyers who expect permanent vacation vibes are usually disappointed.

Community takes work. Vacationing means you don't build community. Full-time life requires it. The residents who thrive after five years are the ones who invested in building a social life intentionally.

Two Things I Tell Every Buyer Weighing Full-Time Coastal Life

First, rent for six months before you buy. A real off-season stretch — say January through June — shows you exactly what daily life will feel like. Buyers who do this consistently make better decisions about neighborhood, budget, and whether the whole idea actually works for them. Buyers who skip this step sometimes regret their specific home choice within the first year.

Second, be honest about the version of coastal life you actually want. If you want daily walks on the sand and beach lunches with friends, live within walking distance. If you want the beach as an occasional weekend feature while your daily life happens elsewhere, buy inland and use the savings for better home features. Match the property to the actual life, not the imagined life.

Key Takeaways

Full-time Grand Strand living delivers real quality-of-life benefits — mild winters, slower pace, community, longer outdoor seasons, meaningful proximity to water — that keep most residents happy for decades. It also comes with real trade-offs that nobody talks about enough. Summer tourist intensity, layered coastal insurance costs, salt-air maintenance, hurricane season awareness, specialist healthcare drives, and off-season quiet all shape daily life in ways vacationers don't experience. Where you specifically live changes the balance dramatically — direct beach-block, residential coastal, inland coastal, and rural-adjacent all serve different priorities. The residents who thrive develop off-peak habits, build indoor lives alongside outdoor ones, sometimes travel out during peak tourist season, and build professional relationships early. The residents who struggle usually assumed vacation life continues year-round. Renting for six months before buying and being honest about the specific version of coastal life you actually want are the two decisions that most reliably lead to a successful long-term full-time move.

About Greg Harrelson

Greg Harrelson is a seasoned Realtor® with more than 30 years of experience serving the Myrtle Beach and Grand Strand markets. As the founder of Century 21 The Harrelson Group, Greg has built his career helping buyers, sellers, and investors achieve success in every corner of the coastal Carolina real estate market. His expertise spans residential homes, investment properties, land development, and coastal condos. Known for his deep local knowledge, innovative marketing strategies, and commitment to personal service, Greg consistently helps clients reach their real estate goals while navigating the ever-changing market with confidence and precision.

Posted in For Buyers, Lifestyle
Aug. 26, 2026

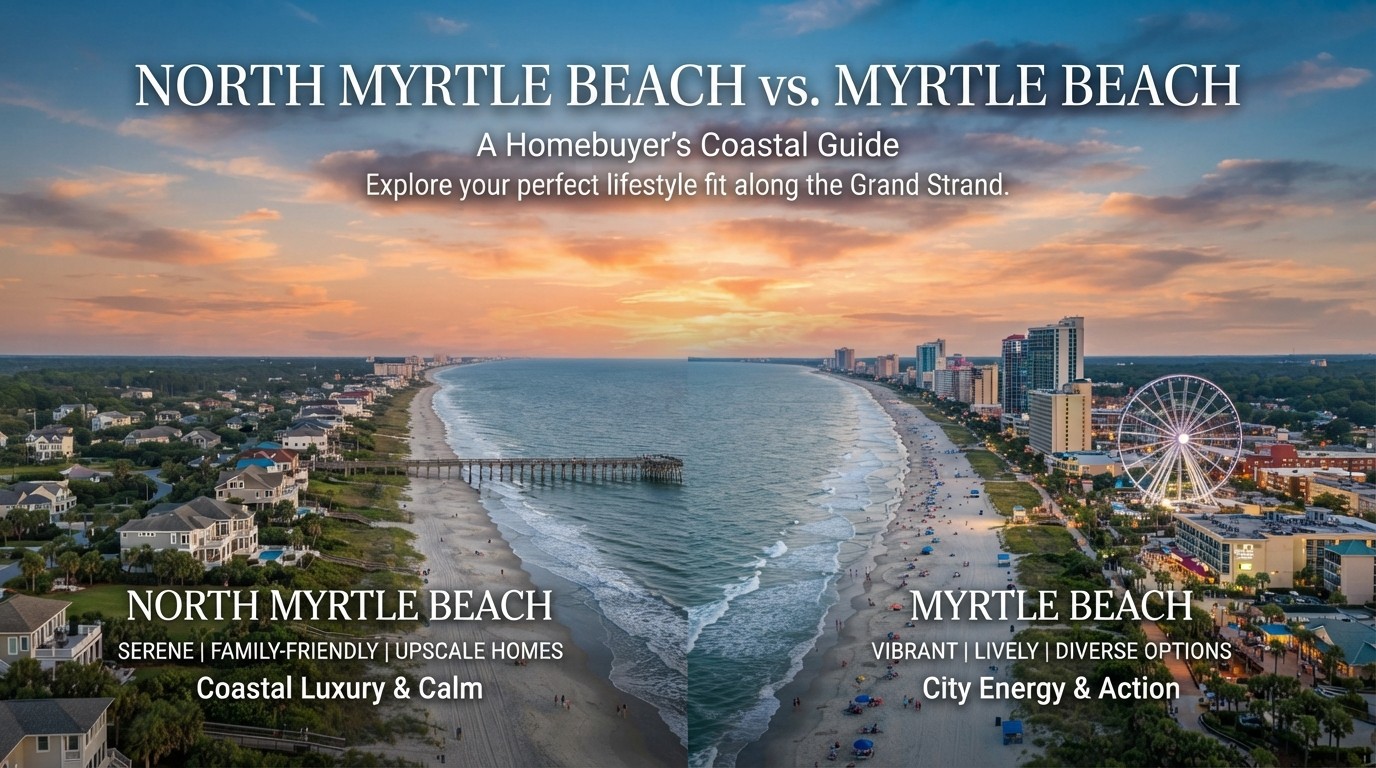
North Myrtle Beach vs. Myrtle Beach for Homebuyers

You've been shopping the Grand Strand and can't decide between North Myrtle Beach and Myrtle Beach itself. Here's the honest answer. They're different cities that share a beach and a zip code range. The lifestyle, the buyer pool, the school zones, and even the daily rhythm all diverge in real ways. If you pick the wrong one for how you actually live, you'll feel it every day. Let me walk you through the differences that matter.

How the Two Cities Actually Feel

Myrtle Beach is a full-tilt resort city. About 35,000 full-time residents but with a tourist population that swells into the millions each year. The boardwalk, SkyWheel, Broadway at the Beach, and the entire Ocean Boulevard corridor exist for visitors first, residents second. If you love the energy, it's hard to beat. If you want quiet, you'll spend a lot of time driving away from your own city.

North Myrtle Beach is smaller and calmer. About 17,000 full-time residents. The city is actually four smaller beach communities stitched together — Cherry Grove, Ocean Drive, Crescent Beach, and Windy Hill — plus an inland corridor west of Highway 17. Tourism is real but doesn't dominate residential life the way it does in Myrtle Beach proper.

The Golf Cart Difference Is Bigger Than It Sounds

Here's what nobody outside the market fully appreciates. North Myrtle Beach allows licensed golf carts on almost every local street. Residents actually use them as a primary local vehicle. Kids ride them to the beach. Neighbors visit each other by cart. You can grab dinner without ever getting in a car.

Myrtle Beach has some cart-friendly pockets but nothing like the culture up in NMB. If the golf cart lifestyle appeals to you, that's a real point for North Myrtle Beach.

School Zones and Family Fit

Both cities sit inside Horry County Schools. Attendance zones are set by exact street address, so verify by property before writing an offer.

For families, Carolina Forest (technically part of the Myrtle Beach area west of the city proper) has some of the strongest school zone reputations in the whole county. That's where a lot of the family-focused new construction landed over the last decade.

North Myrtle Beach schools have solid reputations too, with the smaller-city advantage of tighter community feel. Class sizes tend to be smaller than the Carolina Forest schools.

If your family shopping is centered on schools first, tour both areas with the specific attendance zone in mind rather than the city name.

North Myrtle Beach vs. Myrtle Beach for Homebuyers

Where Full-Time Residents Actually Land

The residential pockets buyers should actually look at differ meaningfully.

Myrtle Beach for full-time living. Carolina Forest is the biggest family draw. Market Common offers walkable neighborhood feel with real community. Grande Dunes appeals to buyers with bigger budgets. Pine Lakes and the Dunes Club corridor offer established residential character. For broader inventory, browse Myrtle Beach real estate.

North Myrtle Beach for full-time living. Cherry Grove for canal homes and quieter beach living. Ocean Drive for walkability and neighborhood identity. Crescent Beach for the calmest of the beach pockets. The inland Barefoot Resort corridor for suburban feel with amenity access. See the full picture at North Myrtle Beach real estate.

What Homes Actually Cost

Here's what I see consistently in the market. Beach-block Myrtle Beach single-family runs materially higher than the inland Myrtle Beach neighborhoods. Beach-block North Myrtle Beach commands premium pricing especially in Cherry Grove and Ocean Drive. Inland North Myrtle Beach in Barefoot and Heron Lake runs meaningfully less than beach-adjacent inventory.

For the same total budget, you can generally buy more house or more land in North Myrtle Beach than in the equivalent Myrtle Beach pocket. That's part of what pulls buyers north.

Insurance, Flood Zones, and Practical Costs

Both cities carry coastal insurance realities — layered homeowner's, wind and hail, and flood policies where applicable. The specific address matters more than the city name.

Cherry Grove canal homes and beach-block North Myrtle Beach properties typically sit in AE flood zones with elevation requirements. Some inland North Myrtle Beach pockets sit in Zone X with friendlier insurance.

Myrtle Beach city runs the same pattern. Beach-block properties carry the coastal insurance load. Carolina Forest and inland Myrtle Beach neighborhoods often qualify for standard coverage without the wind pool or flood requirements.

Which Buyer Types Fit Each City

Two things I tell every buyer choosing between these cities.

Pick Myrtle Beach if you want resort energy, deeper retail and restaurant options, easier access to Grand Strand Medical Center specialists, and the broadest housing variety at every price point. Also if Carolina Forest schools are the specific draw for your family.

Pick North Myrtle Beach if you want a smaller-city residential feel, real golf cart culture, tighter neighborhood community, quieter beach access, and often more house for the dollar on beach-adjacent inventory.

Buyers who value convenience and variety often pick Myrtle Beach. Buyers who value community and quieter daily life often pick North Myrtle Beach. Neither is objectively better — they're different cities that serve different buyers.

What Buyers Underestimate About Each

Myrtle Beach summer traffic. If you live along the Highway 17 Business or Ocean Boulevard corridor, June through August you'll feel it every day. Plan drives with buffer time built in.

North Myrtle Beach off-season quiet. From November through February, the city gets noticeably quieter. Some buyers love that. Others find it more isolating than they expected. Visit in the off-season before you commit if you're used to a busier residential environment.

Two Things I Tell Every Buyer Choosing Between the Two

First, spend a weekday and a weekend in each city before writing an offer. The rhythm on a Tuesday morning tells you more about full-time living than a Saturday tour ever will. Buyers who visit only on weekends see one version. Buyers who see both make better decisions.

Second, drive your realistic daily route. Grocery, healthcare, kids' activities, work if you have a commute. The 15-minute drive that seems fine on a scouting visit gets old fast when you make it three times a week. Test the daily patterns before committing.

Key Takeaways

  • Myrtle Beach and North Myrtle Beach are different cities with different rhythms, buyer pools, and residential character despite sharing a coast
  • Golf cart culture in North Myrtle Beach is a real lifestyle feature Myrtle Beach doesn't fully match
  • Both share Horry County Schools, but attendance zones vary by exact address — verify before writing an offer
  • Myrtle Beach residential landing zones include Carolina Forest, Market Common, Grande Dunes, and Pine Lakes
  • North Myrtle Beach residential pockets include Cherry Grove, Ocean Drive, Crescent Beach, and the inland Barefoot corridor
  • For the same budget you can generally buy more in North Myrtle Beach than in the equivalent Myrtle Beach pocket
  • Coastal insurance and flood zone realities apply to both cities based on specific address, not city name
  • Visit each city on both a weekday and a weekend and drive your realistic daily route before choosing

About Greg Harrelson

Greg Harrelson is a seasoned Realtor® with more than 30 years of experience serving the Myrtle Beach and Grand Strand markets. As the founder of Century 21 The Harrelson Group, Greg has built his career helping buyers, sellers, and investors achieve success in every corner of the coastal Carolina real estate market. His expertise spans residential homes, investment properties, land development, and coastal condos. Known for his deep local knowledge, innovative marketing strategies, and commitment to personal service, Greg consistently helps clients reach their real estate goals while navigating the ever-changing market with confidence and precision.

Aug. 25, 2026

Understanding SC Property Tax as a New Buyer

You're buying your first South Carolina home and someone told you the property tax structure works differently here than most other states. They're right. South Carolina has one of the more unusual property tax systems in the country, and if you don't understand it before closing, you can leave real money on the table for years. Here's how it actually works and what you need to do to get the right rate on your home.

The Two Assessment Ratios That Change Your Tax Bill

South Carolina taxes residential real estate at one of two different assessment ratios based on how the property is used.

Primary residence: 4 percent assessment ratio. This is the friendly rate. It applies when the property is your actual primary home.

Non-primary residence: 6 percent assessment ratio. This applies to second homes, investment properties, vacation homes, and any residential property that isn't your primary home.

The difference is significant. On the same home, the tax bill under the 6 percent rate can run roughly one and a half times what it would under the 4 percent rate. Over a decade of ownership, that adds up to thousands of dollars either way.

Why This Matters Especially in the Grand Strand Market

Here's what makes this specifically important along the Grand Strand. A lot of our buyers are relocating from other states, and many of them don't move immediately after closing. Some plan to make the home their primary residence eventually but not right away. Others buy as a vacation home or investment and never intend it to become primary.

The tax rate follows the actual use, not the intent. If you close on a home and file the paperwork to declare it your primary residence, you pay the 4 percent rate. If you don't file, or if the home isn't actually your primary residence, you pay 6 percent by default.

New buyers relocating from the Northeast, Midwest, or Florida often don't realize this is a paperwork step they have to actively complete. They pay 6 percent for a year or two before figuring out they qualified for 4 percent the whole time.

How the Legal Residence Exemption Actually Works

South Carolina requires you to file for the legal residence exemption with your county assessor's office to get the 4 percent rate. In Horry County, that means filing an application through the county assessor.

What you need to submit:

  • Legal residence application form
  • Proof of ownership (typically the recorded deed)
  • Proof you actually live there — utility bills, driver's license update, vehicle registration all in your name at that address
  • Sometimes a copy of your most recent tax return showing the address

The county has documentation requirements to make sure people don't claim the primary residence rate on homes they don't actually live in. It's not a rubber stamp. If the county doesn't see the pattern of actual residency, they'll deny the application.

Timing Matters

You must file for the legal residence exemption after closing but the timing is important. In most counties you have until a specific deadline each year to file for the current tax year's rate. Miss the deadline and you're paying 6 percent for that full year even if you filed a day later.

My advice to every new buyer: file the paperwork within the first 30-60 days of closing. Don't wait. The application process typically takes a few weeks to a few months to complete depending on how backed up the assessor's office is.

Additional Property Tax Benefits

Beyond the 4 percent versus 6 percent ratio, South Carolina has some additional property tax benefits worth knowing about.

Homestead exemption for buyers 65 and older, disabled, or legally blind. This exempts a portion of the home's fair market value from property tax. It's separate from the legal residence exemption and requires its own application. If you qualify, apply as soon as you close.

Certain veterans qualify for additional property tax exemptions or reductions. Check with your county assessor about specific programs.

Agricultural use assessments apply to rural properties used for actual agriculture. This can dramatically reduce property tax on land that qualifies. If you're buying rural acreage, ask your agent whether the property has current agricultural assessment and what would happen if you kept or dropped it.

What Your Property Tax Actually Funds

South Carolina property tax funds local government services — schools, county services, fire, police, roads. The rate is set at the local level, so the exact millage rate varies by county and even by specific taxing district within the county.

For most Grand Strand primary residences, total annual property tax comes out to a small percentage of the home's fair market value once the 4 percent assessment ratio and applicable exemptions are applied. Non-primary residences pay meaningfully more.

For broader market context, browsing Conway real estate or Myrtle Beach real estate shows the full range of home values across the region.

Understanding SC Property Tax as a New Buyer  Common New-Buyer Mistakes

The mistakes I watch new SC buyers make repeatedly:

  • Assuming the closing attorney handles the legal residence application. They don't. That's on you.
  • Waiting until the following tax year to file, missing a full year of the 4 percent rate
  • Not updating driver's license, voter registration, and vehicle registration to the new address. County assessors look at these documents to verify residency
  • Claiming primary residence on a home that isn't actually primary. County audits catch this and the back taxes and penalties are meaningful
  • Missing the homestead exemption for buyers 65 and older who would otherwise qualify
  • Not understanding what happens to agricultural assessment when you buy rural property

Two Things I Tell Every New SC Buyer About Property Tax

First, file the legal residence application in the first 30-60 days after closing. Not next spring. Not when you get around to it. Set a calendar reminder before you leave the closing table. This one action can save you thousands over the years you own the home.

Second, update all your identification documents to the new address quickly. Driver's license, voter registration, vehicle registration, banking documents. The county needs to see the pattern of you actually living there. The more documentation lines up with the new address, the smoother the residence exemption application goes.

Key Takeaways

  • South Carolina taxes primary residences at 4 percent and non-primary at 6 percent — the difference is significant over years of ownership
  • The 4 percent rate requires filing a legal residence application; it's not automatic and the closing attorney doesn't do it for you
  • File within 30-60 days of closing and don't miss the county deadline for the current tax year
  • Documentation needed: application form, proof of ownership, proof of residency (utility bills, updated driver's license, vehicle registration)
  • Homestead exemption offers additional reduction for buyers 65 and older, disabled, or legally blind
  • Veterans may qualify for additional exemptions; check with the county assessor
  • Agricultural use assessments apply to qualifying rural properties and can dramatically reduce tax
  • Update driver's license, voter registration, and vehicle registration quickly to support your residence application

Frequently Asked Questions

How do I file for the 4% primary residence tax rate in South Carolina?

File a legal residence application with your county assessor's office after closing. In Horry County you can do this through the assessor's office directly. You'll need proof of ownership, proof of residency (utility bills, updated ID), and to complete the application form. Do it within the first 30-60 days after closing so you don't miss the tax year deadline.

Can I have two primary residences for tax purposes?

No. You can only claim one primary residence at a time for SC property tax purposes. If you have a home in another state where you also claim primary residence, the SC assessor will typically deny your legal residence application here. You have to pick one.

What happens if I claim primary residence but don't actually live there?

The county can audit and typically will if the paperwork doesn't line up. If they determine the home isn't actually your primary residence, they'll charge back taxes at the 6 percent rate plus penalties and interest. Don't claim primary residence on a home that isn't actually your primary home.

Does the tax rate change when I sell?

The new owner has to file for their own legal residence exemption if they want the 4 percent rate. Your rate ends when you no longer own the home. If the new owner doesn't file, they pay 6 percent by default.

How is my SC property tax bill actually calculated?

Fair market value multiplied by the assessment ratio (4 or 6 percent) gives you the assessed value. That assessed value is then multiplied by the local millage rate to get your annual tax bill. Millage rates vary by county and specific taxing district, so two similarly-valued homes in different areas can have different tax bills.

About Greg Harrelson

Greg Harrelson is a seasoned Realtor® with more than 30 years of experience serving the Myrtle Beach and Grand Strand markets. As the founder of Century 21 The Harrelson Group, Greg has built his career helping buyers, sellers, and investors achieve success in every corner of the coastal Carolina real estate market. His expertise spans residential homes, investment properties, land development, and coastal condos. Known for his deep local knowledge, innovative marketing strategies, and commitment to personal service, Greg consistently helps clients reach their real estate goals while navigating the ever-changing market with confidence and precision.