Conway, SC Real Estate News 

Century 21 McAlpine Blog

The Agents and Staff at Century 21 McAlpine love our area and one another! We hope to share some of our daily activities with you and see how we might better serve our community!


June 16, 2026

Why More Families Are Leaving Big Cities for Horry County

The relocation calls I take now don't sound the way they used to. Five or six years ago I'd hear from retirees a decade out from their last working year, calling because a friend bought in Myrtle Beach and they wanted to see what was available. Today I'm talking to families in their thirties and forties with remote jobs, school-age kids, and a real plan to move within the next twelve months. They're coming from the Northeast, the Mid-Atlantic, the Midwest, and increasingly from South Florida. The pattern is consistent enough now that I want to lay out what's driving it, what they're finding when they get here, and where they're actually landing.

Why Horry County Specifically

Buyers don't usually start by searching "Horry County, SC." They start by searching Myrtle Beach. What pulls them inland is the same thing that's pulled in-state buyers off the immediate coast for years: more land, lower property taxes, milder insurance costs, and neighborhoods that actually feel like neighborhoods. By the time these families have visited two or three times, they've usually figured out that Conway, Carolina Forest, Longs, and Aynor offer a different lifestyle than the resort strip.

South Carolina's property tax structure is part of the math too. Primary residences here are assessed at 4 percent of value, which is substantially friendlier than the property tax bills these families are leaving in New Jersey, Long Island, suburban Chicago, or northern Virginia. On a $400,000 home, the annual property tax difference between Horry County and many of those origin markets can run $4,000 to $8,000 a year. That's real money that ends up paying for kids' activities or a vacation.

What's Actually Driving the Move

The job piece is the unlock. Remote and hybrid work didn't fade after 2022 the way some people predicted. The families relocating to Horry County now are mostly in roles where 100 percent or 80 percent remote is permanent. The 20 percent in-office days, when they exist, are often a flight away rather than a daily commute. Myrtle Beach International handles the major hubs well enough that a once-or-twice-a-month commute is workable.

School-age kids matter too. Horry County Schools has invested heavily in new construction over the last decade. Buyers shopping Carolina Forest real estate almost always cite the schools as the primary draw. Families looking for smaller-town schools land in Conway real estate or further west toward Aynor real estate, where the school identity is part of the appeal.

Cost of housing is the obvious one. A 2,400 square-foot home with a yard runs roughly half of what the same house costs in the better suburbs these families are leaving. That difference, plus the tax difference, often funds the down payment and the move itself.

Where Families Are Actually Landing

From what I've watched closing after closing, the landing zones split fairly cleanly:

Carolina Forest pulls the buyers who want newer construction, predictable HOA amenities, and tighter school zone identity. The trade-off is smaller lots and a more suburban feel. For families coming from a corporate suburb, this is the most familiar landing pattern.

Conway pulls the buyers who want a real downtown, a historic district, more lot variety, and a slightly slower pace. CCU shapes the rhythm of the town and the buyers who land here tend to value that. Wild Wing Plantation, Carsens Ferry, and the historic streets near Main Street are the most common pockets.

Longs pulls the buyers who want new construction at a lower price point with a short drive to North Myrtle Beach. The Highway 31 connector changed the math for this area and families realized they could live in Longs real estate communities and still be at the beach in fifteen minutes.

Aynor and Loris pull the buyers who want acreage, privacy, and a school identity that hasn't been diluted by rapid growth. These buyers are usually a step further removed from city life in their origin too — they weren't living in dense urban cores, they were in semi-rural exurbs already.
Why More Families Are Leaving Big Cities for Horry County

The Trade-Offs Families Discover After They Move

I always tell families honestly: the move isn't free. The trade-offs that come up most often after closing are:

Healthcare specialists. Grand Strand Medical Center, Conway Medical Center, and McLeod Loris are all solid, but for very specialized care, families sometimes drive to Charleston or fly to Charlotte. If you have a complex medical condition in the family, factor this in before you commit.

Shopping and culture. Big-box and chain retail is everywhere along the Highway 17 and 501 corridors, but specialty retail, museum-quality cultural institutions, and certain international cuisines are limited compared to a major metro. Families adjust, but the first six months can be a shift.

The driving. Distances are short by Northeast standards but a lot longer than what some buyers expect. Conway to North Myrtle Beach is 30 minutes. Conway to the Charleston suburbs is over two hours. Plan accordingly.

Two Things I Tell Every Relocating Family

First, rent before you buy if you can. Even a three-month rental in Conway or Carolina Forest gives you the chance to learn which side of town actually fits your daily life. I've watched families buy on a single weekend visit and end up wishing they'd landed five miles in a different direction.

Second, visit in August. The Conway heat and humidity in late summer is real. The bugs are real. The tropical weather is real. If a family decides they still love it in August, they're going to love it the rest of the year. If August breaks them, better to know before closing.

For buyers in earlier stages of the research process, exploring the broader Myrtle Beach real estate map alongside the inland options is the comparison most families need to make their final landing-zone decision.

Key Takeaways

The wave of families leaving big cities for Horry County is no longer a pandemic story — it's a structural one driven by remote work, the South Carolina property tax structure, school investment, and the housing cost gap with the markets they're leaving. They're landing in four main pockets: Carolina Forest for newer construction and tight school zones, Conway for downtown character and lot variety, Longs for affordability with beach access, and Aynor or Loris for real space and rural character. The trade-offs after the move are healthcare specialists, specialty retail, and slightly longer drives than buyers expect. The families who do best rent before they buy and visit at least once in late summer. Horry County keeps absorbing this growth, but the right landing-zone fit depends on what these families actually value once the relocation excitement settles down.

About Greg Harrelson

Greg Harrelson is a seasoned Realtor® with more than 30 years of experience serving the Myrtle Beach and Grand Strand markets. As the founder of Century 21 The Harrelson Group, Greg has built his career helping buyers, sellers, and investors achieve success in every corner of the coastal Carolina real estate market. His expertise spans residential homes, investment properties, land development, and coastal condos. Known for his deep local knowledge, innovative marketing strategies, and commitment to personal service, Greg consistently helps clients reach their real estate goals while navigating the ever-changing market with confidence and precision.
June 15, 2026

When is the best time to sell a Conway, SC condo

Conway condos sell on a different calendar than Conway single-family homes, and the difference matters when you're trying to decide when to list. The buyer pool is more split: parents shopping housing for Coastal Carolina University students, snowbirds who want a low-maintenance second home, downsizing retirees, and investors looking for steady long-term tenants. Each of those buyer types has its own seasonal pattern, and a condo seller who understands all four can pick the timing that maximizes price. Here's how I help condo sellers in Conway think about it after three decades of listing in this town.

The Short Version for Conway Condo Sellers

The strongest window to list a Conway condo runs late February through early June, with a real spike in May and June driven by parents finalizing housing for CCU's fall semester. The second-best stretch is mid-September through mid-November, when snowbirds and downsizing retirees make their decisions. The slowest stretch is mid-November through January, similar to the single-family market but a few weeks longer because investors rarely close around the holidays.

The mid-summer slowdown that hits Conway single-family homes is less pronounced in the condo market because parent-buyers shopping for CCU students push real activity into June and July. That's a genuine difference worth knowing.

The CCU Effect on Condo Timing

This is the biggest single difference between Conway condos and Conway single-family homes. Parents who decide to buy a condo instead of paying student housing for four years tend to start shopping seriously in April. They want to close in June or July so their student can move in before the fall semester. That demand window pushes condo activity from May through July in a way that doesn't happen for traditional family homes.

If your Conway condo is within a 10-minute drive of campus, list in early-to-mid April to catch the bulk of this parent-buyer wave. The units that sell fastest in this window are 2- and 3-bedroom layouts under $300,000 — that's the sweet spot for the parent math.

The Snowbird and Retiree Cycle

Snowbirds who spend summers in the Northeast and Midwest start touring Conway condos in earnest from late September through November. They've already lived through one cold-weather season and decided to buy. They've spent the summer talking with their adult kids about it. By October, they're ready.

This buyer is often a strong one. They tend to be cash buyers or have substantial down payments. They've done their research. They close quickly. The downside for sellers is the pool is smaller than the spring pool, but the conversion rate from showing to offer is noticeably higher.

For condos in walkable areas — particularly the few units near downtown Conway and the Riverwalk — this fall window often outperforms spring on price per square foot. Browsing the current Conway condos for sale inventory gives you a sense of how competitive your specific price band looks heading into either window.

The Investor Buyer's Calendar

Investors shopping Conway condos run their own clock. Two windows tend to drive their activity: spring tax season, when refunds and 1031 exchange decisions kick in, and end-of-year, when investors look for a December 31 closing to pull deductions into the current tax year. The end-of-year investor window is one of the few reasons to list in late November or December despite the otherwise slow market.

Investor buyers care almost entirely about rental income, HOA dues, and rental restrictions. The best move when targeting them is to have actual rental history or comparable rent data ready in the listing package, plus a fresh copy of the HOA's rental rules. I've watched investor offers come in 5% to 8% higher than equivalent owner-occupant offers when the seller comes prepared with that information.

When is the best time to sell a Conway, SC condo

HOA Activity Affects Your Timing

One thing condo sellers underestimate: special assessments, dock or roof projects, and any HOA action that's pending can quietly kill a listing's momentum. Buyers and their lenders will pull the HOA's documents during the contingency period, and a fresh assessment dropping in the middle of escrow is a deal-breaker more often than not.

If you know your building has a vote coming on a major project, time your listing to either close before it or wait until the assessment is finalized and the dollar amount is known. Selling in the limbo between "they're talking about it" and "it's been voted on" is the worst possible spot.

Which Conway Condo Segments Move Fastest

The 2-bedroom, 2-bathroom layout in the $180,000 to $260,000 range remains the most active segment year-round. That price point hits the CCU parent buyer, the downsizing retiree, and the rental investor all at once. Three of the four buyer types are looking in this band.

Higher-end Conway condos (above $350,000) move more on the snowbird and second-home calendar than the CCU calendar. List those in October if possible.

For sellers comparing their condo to the broader market, the Conway real estate inventory gives you context on how condos are pricing relative to single-family homes in similar bands.

Two Things I Tell Every Conway Condo Seller

First, the condo HOA disclosure package is part of your listing strategy, not a closing-period afterthought. Pull the bylaws, the rental rules, the last two years of meeting minutes, the most recent reserve study, and the current dues and assessment history before you go live. Buyers who can review that package in the first 48 hours decide to write offers faster than buyers who have to wait two weeks.

Second, photograph the condo with the actual buyer in mind. A condo that targets CCU parents should show the bedrooms as bedrooms, not as workspaces. A condo that targets snowbirds should show the living space relaxed, not staged like a rental. The photo set that works for an investor (showing space and durability) is different from the photo set that works for a retiree (showing comfort and easy living). Pick your primary buyer first, then shoot for that buyer.

Key Takeaways

  • The strongest window to list a Conway condo runs late February through early June, peaking in May-June for CCU parent buyers
  • Mid-September through mid-November is the second-best window, dominated by snowbirds and downsizing retirees
  • Investors run on tax-driven cycles: spring tax season and December year-end closings
  • 2-bedroom, 2-bathroom condos in the $180k-$260k range are the most active segment year-round
  • Higher-end condos above $350,000 follow the snowbird calendar more than the CCU calendar; October listings often work best for these
  • HOA activity (special assessments, pending votes, dock or roof projects) can kill a listing's momentum; time around the HOA calendar, not just the market calendar
  • Pull the full HOA document package before listing, not during escrow — buyers move faster when they can review it on day one

About Greg Harrelson

Greg Harrelson is a seasoned Realtor® with more than 30 years of experience serving the Myrtle Beach and Grand Strand markets. As the founder of Century 21 The Harrelson Group, Greg has built his career helping buyers, sellers, and investors achieve success in every corner of the coastal Carolina real estate market. His expertise spans residential homes, investment properties, land development, and coastal condos. Known for his deep local knowledge, innovative marketing strategies, and commitment to personal service, Greg consistently helps clients reach their real estate goals while navigating the ever-changing market with confidence and precision.
Posted in For Sellers
June 12, 2026

When is the best time to sell my Conway, SC home

Almost every seller I sit down with in Conway asks the same question before we talk about anything else: when should I list? It's the right question to ask, and the answer is more nuanced than the generic "spring is best" advice you'll read online. Conway's market has its own rhythm, driven by Coastal Carolina University's academic calendar, the relocation buyers coming down from the Northeast and Midwest, the snowbird cycle, and the school zones inside Horry County. After thirty-plus years of listing homes in this town, here's how I actually think about timing.

The Short Version

For most Conway single-family homes, the strongest months to list are mid-February through early May. That window captures the spring relocation buyers, the families trying to close before the next school year, and the snowbirds who've decided over the winter to make Conway their full-time home. A close second is mid-September through early November, when school-year buyers who didn't pull the trigger in spring come back to the table and out-of-state retirees finalize their move before the holidays.

The weakest stretches are late June through August (when families with kids in school have already moved or paused) and mid-November through early January (when the holidays slow everyone down). That doesn't mean don't list — sometimes there's a real reason — but it does mean expect a longer market time.

Why Conway's Spring Window Works So Well

Buyers who drove down to Conway over Thanksgiving and Christmas often spend December and January talking themselves into making the move. By February they've made the decision and are reaching out to agents. By March and April they're under contract. If your home is listed in early March, you catch this wave at exactly the right moment.

The school calendar drives a real piece of this. Families with kids want to close, move, and settle in before the new school year. Horry County schools start in August, which means closing by mid-July is the goal. Work backwards: that's a contract in May or June, which means listing in late February or March if you want to be the home they pick.

The yard works in your favor in spring too. Conway's azaleas, dogwoods, and crepe myrtles bloom March through May. Listing photos shot in late March show your property at its best, and curb appeal moves homes in this market more than people realize.

The Fall Window Most Sellers Underestimate

September through November is the second-best stretch and it's quieter, which means less competition. Snowbirds who summer in the Northeast and Midwest spend September and October making decisions for the coming winter. Retirees finalizing their relocation want to be closed and moved before the holidays. The buyers in this window are usually more decided, less price-sensitive, and faster to close.

For sellers in the historic Conway district or near downtown, fall can actually outperform spring on price per square foot. The buyers who come down in October already know they want walkable Conway. They aren't shopping fifteen properties — they're shopping three or four.

When is the best time to sell my Conway, SC home

What Actually Slows Down Summer

July and August get hot, humid, and slow. The buyers who needed to be closed before school started already are. The buyers thinking about a relocation usually wait until fall when the weather cools and their kids are settled. Showing activity drops noticeably in these months, and homes that sit on the market through August tend to require price adjustments to draw fall buyers back.

There's a Conway-specific layer here too: hurricane season. Buyers from out of state get nervous about closing during peak season (August and September). Even when nothing major is forecast, I've watched offers slow down for two weeks after every named storm in the Atlantic, regardless of whether it actually threatens us.

Which Conway Neighborhoods Buck the Pattern

Family-friendly neighborhoods like Wild Wing Plantation, Carsens Ferry, and Astoria Park follow the school-year pattern most strictly. Spring is the clear winner, with a strong fall second.

Historic Conway and the downtown-adjacent streets follow a different rhythm. Those homes pull more retirees, second-home buyers, and CCU faculty — buyers who don't have school-year pressure. Late summer and early fall actually work well in these pockets.

The no-HOA homes in Conway and rural properties off Highway 905 follow yet another pattern. Land-and-acreage buyers move year-round, and winter listings often sell because the buyer pool isn't seasonal.

Two Things I Tell Every Conway Seller About Timing

First, list a week before the comparable inventory hits the market, not the same week. If everyone in your neighborhood waits until the first week of March, you list at the end of February. Being the first fresh listing in a price band brings showings that the second and third listings have to compete for.

Second, your home only gets one shot at being a "new listing." The first two weeks on market generate the most showing activity by a wide margin, and a price adjustment three weeks in never recovers what a properly-priced launch would have captured. The right list date with the right price beats the best date with the wrong price every single time.

For sellers who want to study current comparable activity before deciding on timing, browsing the Conway real estate map gives you a feel for how many homes are sitting in your price band right now and how recently they listed.

Key Takeaways

For most Conway single-family homes, mid-February through early May is the strongest listing window, with mid-September through early November as a quieter but often higher-quality second window. The school calendar, the snowbird cycle, and the Coastal Carolina University rhythm all drive these patterns. Summer is slower, especially July and August, and the holiday window from mid-November through early January is the weakest stretch of the year. Family neighborhoods follow the school cycle most strictly. Historic downtown Conway, rural acreage, and no-HOA properties follow looser patterns and can do well outside the typical windows. The best advice I give every seller is to list a little earlier than the rest of your neighborhood, price the home correctly from day one, and treat the first two weeks on the market as the only first impression you get.

Frequently Asked Questions

How long does the average Conway home take to sell?

It depends heavily on price band and condition, but in a balanced market, well-priced Conway homes under $400,000 typically go under contract within 30 to 45 days of listing. Higher price points (above $600,000) generally take 60 to 90 days. A home that sits much longer than the local average usually has a price or condition issue, not a timing issue.

Should I list before or after I move out?

If you can list while still living in the home and keep it show-ready, that's usually preferable — occupied homes show more naturally and buyers respond better to a lived-in feel. If you're moving for work or buying out of the area first, vacant is fine, but invest in light staging and lawn care. Empty homes with neglected yards lose buyer interest fast.

Does the Coastal Carolina University academic calendar affect Conway home sales?

Yes, particularly for homes within 10 minutes of campus. Parent-buyer activity peaks May through July as families lock in housing for the fall semester. Faculty relocation activity peaks late spring. If your home appeals to either buyer pool, listing in March or April catches both.

Are summer listings really worse, or is it just slower for everyone?

Both. Showings drop in July and August, but inventory drops too, which means well-priced summer listings still sell. The difference is that mediocre listings don't get the buyer urgency they would in spring, so summer is unforgiving on overpricing.

How much does listing in spring versus winter actually change my sale price in Conway?

From the data I track, spring listings in Conway typically sell within 1% to 3% of asking price, while winter listings often close with 3% to 6% in price reductions before going under contract. The dollar difference on a $400,000 home can run $8,000 to $20,000 depending on how disciplined the pricing is.

About Greg Harrelson

Greg Harrelson is a seasoned Realtor® with more than 30 years of experience serving the Myrtle Beach and Grand Strand markets. As the founder of Century 21 The Harrelson Group, Greg has built his career helping buyers, sellers, and investors achieve success in every corner of the coastal Carolina real estate market. His expertise spans residential homes, investment properties, land development, and coastal condos. Known for his deep local knowledge, innovative marketing strategies, and commitment to personal service, Greg consistently helps clients reach their real estate goals while navigating the ever-changing market with confidence and precision.
Posted in For Sellers
June 11, 2026

Best New Construction Communities in Longs

Longs has quietly become one of the busiest new construction pockets in our entire market. Drive up Highway 9 or out Highway 905 past Loris on any weekday morning, and you'll see grading crews working three or four subdivisions inside a five-mile stretch. The Longs growth story has been building for over a decade, but the last three years have changed the inventory mix in real ways. Buyers who priced themselves out of North Myrtle Beach and Little River keep landing here. Here's how I help them sort through what's worth a look.

Why Longs Took Off in the First Place

Longs sits roughly 15 to 20 minutes inland from North Myrtle Beach, which is the sweet spot for buyers who want coastal access without the property tax bill and traffic of the immediate beach corridor. The land was cheaper than it should have been for years, which is why the national builders moved in heavy. You also get easier flood zone designations than the coastal pockets — most of Longs sits in Zone X — and that simplifies financing and insurance.

The road network finally caught up too. Highway 31 connects Longs to the south end of North Myrtle Beach in about 12 minutes once you're on it. That single road changed the math for buyers comparing Longs to communities ten miles closer to the water. 

Best New Construction Communities in Longs

Polo Farms

Polo Farms is the community I bring up first with most buyers who want a balance of newer construction, larger lots, and amenities. Lots run noticeably bigger than the typical national builder community. The price points have crept up but still tend to land in the high $300s to mid $500s for what you get. The trade-off is the drive to grocery and shopping is longer than buyers expect on the first visit.

The Park and The Reserve at Long Bay

Long Bay has been delivering homes for years and matured into one of the more recognizable golf community options on the north end. The Park at Long Bay and The Reserve at Long Bay sit next to the course and pull a steady mix of full-time retirees and second-home buyers. The HOA is more active than most Longs communities, which buyers either appreciate or find heavy depending on temperament.

Heritage Park

Heritage Park at Longs has been one of the steadier sellers for D.R. Horton-style buyers — predictable layouts, predictable pricing, decent amenity package. Inventory turns reasonably quickly and the pool is genuinely used. The community gets a lot of relocation buyers from the Northeast and Midwest who want something move-in ready without the volatility of waiting on a custom build.

Cypress Ridge and Chestnut Farms

These are two pockets I send buyers to when they want a quieter feel and a slightly older "new" — meaning homes built in the last 5 to 8 years that have settled, but still have plenty of life left. Cypress Ridge is on the more affordable side and works well for first-time buyers or downsizers. Chestnut Farms offers slightly larger floor plans for the same price band.

Newer Pockets to Watch

A few smaller communities are growing quickly enough that they're worth knowing about even if they aren't quite as established yet:

  • Carrington Woods and Avery Woods — both filling in steadily with mid-tier single-family product
  • Colonial Charters — a more established option that still has resale opportunity
  • Chestnut Estates at Mesa Raven — newer subdivision worth a drive-through
  • Pine Needle Estates — quieter pocket with a different feel
  • Ivy Woods and Buck Creek — popular with relocation buyers wanting smaller lots and lower maintenance

For the broader picture, browse the full inventory of Longs real estate to see what's currently for sale across all of these. The market in Longs moves quicker than buyers expect on competitively-priced homes, and the active listings list updates frequently.

Two Things I Tell Every Longs New Construction Buyer

First, the lot premium is real and worth thinking through. A standard interior lot might list at base, but a corner, pond view, or wooded buffer lot can add $5,000 to $25,000. Some lots are worth the premium for resale and some aren't. Pond views, in particular, hold up well on resale; corner lots are more of a personal preference call.

Second, the design center adds up faster than buyers realize. National builders price the base home aggressively because they know the average buyer will add $20,000 to $50,000 in finishes. The buyers who finish under that average usually walk in with a clear list and stay disciplined. The buyers who pick options room by room blow through it.

Key Takeaways

  • Longs has become one of the fastest-growing new construction pockets in Horry County, driven by Highway 31 access to North Myrtle Beach and easier flood zone designations
  • Polo Farms, The Park at Long Bay, and The Reserve at Long Bay lead the higher-amenity options
  • Heritage Park, Cypress Ridge, and Chestnut Farms cover the predictable mid-tier price band
  • Newer growth pockets to watch include Carrington Woods, Avery Woods, Colonial Charters, Chestnut Estates at Mesa Raven, Pine Needle Estates, Ivy Woods, and Buck Creek
  • Most price points land in the mid $200s to mid $500s, with amenity-heavy communities running higher
  • Lot premiums and design center upgrades typically swing the final number more than the base price; budget accordingly

About Greg Harrelson

Greg Harrelson is a seasoned Realtor® with more than 30 years of experience serving the Myrtle Beach and Grand Strand markets. As the founder of Century 21 The Harrelson Group, Greg has built his career helping buyers, sellers, and investors achieve success in every corner of the coastal Carolina real estate market. His expertise spans residential homes, investment properties, land development, and coastal condos. Known for his deep local knowledge, innovative marketing strategies, and commitment to personal service, Greg consistently helps clients reach their real estate goals while navigating the ever-changing market with confidence and precision.
Posted in For Buyers
June 10, 2026

How Flood Zones Affect Home Values in Horry County

I've been writing offers in Horry County for more than thirty years, and the question that keeps coming up over and over is the same one: how much does this flood zone actually hurt the value? It's a fair question, because the answer changes a lot depending on the street, the elevation, the lender, and frankly, how recent the buyer's memory of Hurricane Florence happens to be. Here's how I walk people through it when they bring me a Horry County address and ask if they should be worried.

What "Flood Zone" Actually Means Here

FEMA divides Horry County into mapped flood hazard areas. The labels that matter most in our market are:

  • Zone X — minimal flood risk. Most homes inland of the Intracoastal in places like Carolina Forest, the higher pockets of Conway, and most of Aynor sit here.
  • Zone AE — a 1% annual chance of flooding, also called the 100-year floodplain. Comes with a base flood elevation the building has to meet or beat.
  • Zone A — high risk, but no detailed elevation data, so insurance pricing depends more on the structure than the published number.
  • Zone VE — coastal high hazard, where wave action is in play. Mostly tight bands along the oceanfront.
  • Floodway — the channel itself. Very limited rebuild rights.

The Waccamaw River corridor, the Intracoastal, and the tidal stretches near Murrells Inlet and Pawleys carry the most AE and VE designations. After the 2015 floods and Florence in 2018, FEMA also updated maps in spots people didn't expect, which moved some long-standing Conway and Bucksport homes from X into AE almost overnight.

How Flood Zone Shows Up in the Sale Price

The honest answer: it depends on the buyer pool. From watching closings, here's what I see consistently:

An AE zone home in a flood-aware neighborhood usually sells for about 5% to 12% less per square foot than a comparable Zone X home one street over. The discount widens when the home is older and on a slab. It narrows when the home is on tall pilings and clearly elevated above the base flood line.

A floodway designation is a different conversation. Those homes often sell well below the surrounding market, sometimes 20% or more, because the rebuild rules make insurance, financing, and future remodels harder. A few of my investor clients specifically hunt these properties when the price drops far enough.

Coastal VE zone homes don't fit the same pattern. Oceanfront buyers usually accept the zone and price it into the deal. The view does most of the heavy lifting on value, and the insurance is a known cost. For coastal buyers shopping Myrtle Beach real estate directly on the sand, the flood line isn't usually a deal-breaker — it's just a budget item.

The Insurance Math That Drives Resale

What really sets the value impact is the annual insurance bill, not the zone label itself. Two homes on the same street can have wildly different premiums because of:

  • First finished floor elevation relative to the base flood elevation
  • Whether there's an enclosure or breakaway walls below
  • The age of the structure and whether it's pre-FIRM (pre-1974 in most of Horry County)
  • Whether the current owner has a grandfathered NFIP policy that may not transfer cleanly

That last one trips up more buyers than people realize. An owner paying $1,200 a year may sell to a buyer who immediately gets quoted $3,800 because the grandfathered rate didn't follow the property. Always pull an elevation certificate and a fresh quote before you remove the inspection contingency.

For broader insurance background that matters in this market, the Conway property insurance page is a useful reference, and your insurance agent can pull the elevation certificate from the seller or order a new one.

Specific Pockets of Horry County to Know

Conway: most of the city is Zone X, but the Waccamaw-adjacent neighborhoods carry AE designations, and Bucksport sits in mixed AE/X depending on elevation. Properties one block off the river can sit in completely different rate classes.

Carolina Forest: largely Zone X, which is one reason it has been the easier-financing pocket of the market for a decade. Some communities, including Carolina Forest-area builds near the Waterway, do touch AE on the back property line, so always pull the parcel map.

Longs and inland Loris: mostly Zone X. A few low-lying spots near tidal creeks fall into AE. If you're shopping Longs real estate, the elevation differences across a single subdivision can be a few feet, which matters more than it sounds.

North Myrtle Beach, Cherry Grove, and Garden City: mixed AE and VE depending on proximity to the dunes and inlet. Cherry Grove canal homes are a special case because of the tidal effect on insurance pricing.

Two Things I Tell Every Buyer in a Flood Zone

First, the listing agent's flood zone answer is not enough. I have my buyers pull the FEMA Map Service Center result by exact street address and request the elevation certificate before they go firm. Verbal answers from anyone, including me, are just starting points.

Second, look at what the home survived, not just what the zone says. A house that came through Florence and Matthew dry is worth more in my eyes than a house in a "safer" zone that hasn't been tested yet. Ask the neighbors. Pull the seller's disclosure twice.

How Flood Zones Affect Home Values in Horry County

Key Takeaways

  • Flood zones in Horry County range from Zone X (minimal) to Zone VE (coastal high hazard), with AE and A being the most common designations along the Waccamaw and Intracoastal
  • AE-zone homes typically sell at a 5% to 12% per-square-foot discount versus Zone X comparables, with the gap widening for older slab homes
  • Floodway designations carry the steepest value impact, often 20% or more, because of rebuild and lending restrictions
  • The real value driver is the insurance premium, not the zone label — elevation certificate, finished-floor height, and grandfathered NFIP policies all matter
  • Conway, Bucksport, Cherry Grove, and Garden City have the most flood-zone activity; Carolina Forest, inland Longs, and Aynor are largely Zone X
  • Always pull the FEMA map by exact street address and get a fresh insurance quote before removing the inspection contingency

Frequently Asked Questions

Do I have to buy flood insurance in Horry County?

If your home is in Zone A, AE, or VE and you have a federally-backed mortgage, flood insurance is required. In Zone X, it's optional but increasingly recommended after the 2015 and 2018 events showed how much rain falls outside the mapped floodplain.

Does a flood zone designation always lower the resale price?

Not always. Elevated newer construction on tall pilings can sell at or above comparable Zone X homes because buyers see the structure itself as proof of risk management. The hit shows up most clearly on older slab homes that haven't been elevated.

Can I appeal a flood zone designation?

Yes, through a Letter of Map Amendment or Letter of Map Revision filed with FEMA. It typically requires a surveyor's elevation certificate showing the lowest adjacent grade is above the base flood elevation. The process takes several months but can change a home's insurance picture materially.

How do I find out my exact flood zone?

Use the FEMA Map Service Center website and search by full street address. The result will tell you the zone, the panel number, and the base flood elevation if one applies. Don't rely on a community-level designation — the line between zones can run through a single block.

What is an elevation certificate and why does it matter?

It's a survey document that records the home's lowest finished floor elevation relative to the base flood elevation. Insurance carriers use it to set premiums. A favorable elevation certificate can save thousands a year in flood insurance, and a missing one usually means the carrier prices in worst-case assumptions.

About Greg Harrelson

Greg Harrelson is a seasoned Realtor® with more than 30 years of experience serving the Myrtle Beach and Grand Strand markets. As the founder of Century 21 The Harrelson Group, Greg has built his career helping buyers, sellers, and investors achieve success in every corner of the coastal Carolina real estate market. His expertise spans residential homes, investment properties, land development, and coastal condos. Known for his deep local knowledge, innovative marketing strategies, and commitment to personal service, Greg consistently helps clients reach their real estate goals while navigating the ever-changing market with confidence and precision.
June 9, 2026

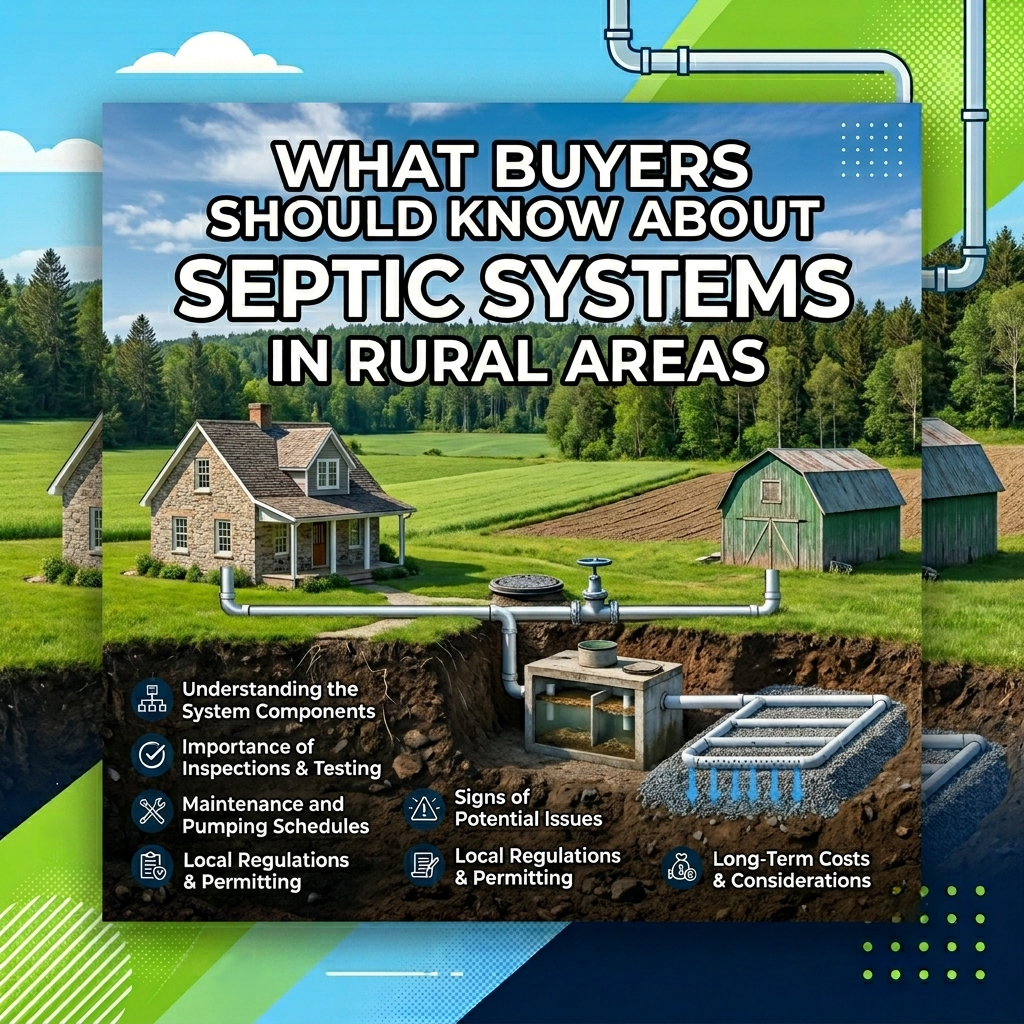
What Buyers Should Know About Septic Systems in Rural Areas

If you've been shopping rural homes in Horry County — Aynor, Loris, Galivants Ferry, the back roads off Highway 905, or the deeper pockets of Longs — odds are good the property runs on septic, not city sewer. I've watched a lot of out-of-state buyers learn this the hard way during the inspection period. It's not a deal-breaker, but it is a real piece of due diligence that I want every rural buyer to understand before they sign anything. After three decades of writing offers out here, here's what I tell people.

Why Septic Is the Norm This Far Inland

City sewer reaches only as far as the utility lines do, and in rural Horry County, that's usually not far. The infrastructure cost of running municipal sewer to a property that sits a mile off the main road just doesn't pencil out. So the home was built with its own underground treatment system — a septic tank and a drain field — and that's what you're buying.

Septic isn't a problem; it's a system. Properly designed, installed, and maintained, a septic system can run quietly for thirty years or more. Poorly maintained or undersized for the home's actual usage, it can fail in ways that are expensive and disruptive. Most of the rural homes I sell in Aynor real estate and Loris real estate are on systems that work fine, but I treat every septic-served property as a separate inspection conversation.

How a Septic System Actually Works

Wastewater leaves the house and enters a buried tank. Solids settle. Liquids flow out into a drain field, where they percolate down through the soil and get treated by the surrounding ground. The tank needs periodic pumping. The drain field needs to stay free of compaction and root intrusion. The soil needs to drain at a usable rate.

The size of the tank is matched to the number of bedrooms in the home, not the square footage. A three-bedroom home requires a smaller tank than a five-bedroom home. If a previous owner added a bedroom without permitting the septic upgrade, the system is now undersized and that becomes the buyer's problem.

The Inspection That Matters

A standard home inspection does not include a septic inspection in most cases. It's a separate scope, often called a septic dye test, septic load test, or full pump-and-inspect. The price runs roughly $300 to $600 depending on the inspector and whether they pump the tank as part of the visit.

What I want a septic inspection to confirm:

  • Tank size matches the bedroom count
  • Tank baffles and lids are intact
  • Drain field shows no surface saturation or odor
  • System handles a real water load without backing up
  • Permits and as-built drawings are on file with DHEC if the home is newer

I tell buyers to insist on this inspection even when the seller swears the system was just pumped. Pumping the tank is maintenance. Inspecting the system is diagnosis. The two are different conversations.

Real Costs Buyers Should Plan For

Maintenance: pumping a residential septic tank every three to five years runs $300 to $500. Skip it for ten years and you risk a clogged tank and a backed-up drain field, which is when costs jump fast.

Repairs: a baffle replacement might be $200 to $500. A new tank lid is similar. A new tank itself can run $2,500 to $5,000 depending on size and access.

Drain field replacement: this is the expensive one. A full drain field replacement on a typical residential lot in this market runs $8,000 to $25,000, with the upper end hitting homes in tight lots or wet soil. This is the cost that turns a routine septic into a real budget event.

Conversion to a pumped or aerobic system: if the soil doesn't perc well, a conventional gravity drain field won't work and the home needs a more complex system that uses a pump. Those systems carry higher install costs and an electric bill, plus annual service contracts.

What Buyers Should Know About Septic Systems in Rural Areas

What Affects Septic Resale Value

Buyers price septic-served homes differently than sewer-served ones, but the gap is smaller in rural areas where everyone is on septic anyway. The discount shows up most when:

  • The system is at the end of its expected life
  • The drain field shows visible issues during the inspection
  • The tank is undersized for the bedroom count
  • The home has been added onto without permitting the septic upgrade
  • The lot's soil drainage is marginal

On the other hand, a recently installed system with permitted as-built drawings and a clean inspection actually adds value because the next buyer sees it as one less unknown. I've had sellers in Longs real estate pull a clean recent septic inspection out of a file folder at closing, and the buyer's anxiety dropped immediately.

Two Things I Tell Every Rural Buyer About Septic

First, ask for the permit and as-built drawing. SCDHEC files include the original permit, the soil percolation test, and a drawing of where the tank and drain field sit on the property. That paperwork tells you what you're really buying. If it doesn't exist, the system was either installed before records, or installed without permits — and both are worth knowing before closing.

Second, walk the property after a heavy rain. If you can manage to visit a candidate house the day after a real downpour, do it. Saturated yards, soft spots over the drain field, or pooled water above the tank all tell you more than any inspection report can.

Key Takeaways

  • Most rural Horry County homes — Aynor, Loris, Galivants Ferry, deeper Longs, back roads off 905 — run on septic, not city sewer
  • Septic is a fine system when designed correctly and maintained, but tank size, drain field condition, and soil drainage all matter
  • A septic-specific inspection ($300-$600) is separate from a standard home inspection and worth insisting on
  • Routine pumping every 3 to 5 years costs $300 to $500; drain field replacement can run $8,000 to $25,000
  • An undersized tank (often from an unpermitted bedroom addition) becomes the buyer's problem after closing
  • Permitted as-built drawings from SCDHEC are the gold standard piece of due diligence
  • Walking the property after a heavy rain reveals more than any inspection report

Frequently Asked Questions

How often does a septic tank need to be pumped?

For most residential households, every three to five years. Larger households, smaller tanks, or homes with garbage disposals running heavily may need pumping more often. Tanks at vacation homes that sit unused most of the year can usually go longer.

Will a bank loan on a home with a septic system?

Yes, conventional, FHA, USDA, and VA loans all routinely finance septic-served homes. FHA and VA may require a satisfactory septic inspection as a loan condition. USDA loans, which are common in rural Horry County, also require functional septic but don't penalize the home for having it.

What happens if a septic system fails after closing?

It's the new owner's responsibility unless a specific representation or warranty in the purchase contract says otherwise. That's why the inspection during the contingency period matters. A failed system after closing isn't typically covered by the seller's disclosure unless the seller knew and didn't disclose, which is hard to prove.

Can a septic-served home be converted to city sewer?

Only if a sewer line runs near the property. Most rural Horry County parcels are too far from utility lines to make conversion practical. If sewer is available, the tap-on fee plus connection costs typically run $5,000 to $15,000 in this market, and some homeowners still choose to stay on a healthy septic rather than convert.

What is an aerobic septic system?

It's a more complex system that uses air pumps to accelerate the breakdown of waste, allowing it to function on smaller drain fields or in soils where conventional gravity systems can't drain. They're more expensive to install (often $15,000 to $25,000) and require annual service contracts, but they're the right answer on lots that would otherwise be unbuildable.

About Greg Harrelson

Greg Harrelson is a seasoned Realtor® with more than 30 years of experience serving the Myrtle Beach and Grand Strand markets. As the founder of Century 21 The Harrelson Group, Greg has built his career helping buyers, sellers, and investors achieve success in every corner of the coastal Carolina real estate market. His expertise spans residential homes, investment properties, land development, and coastal condos. Known for his deep local knowledge, innovative marketing strategies, and commitment to personal service, Greg consistently helps clients reach their real estate goals while navigating the ever-changing market with confidence and precision.
June 8, 2026

Oceanfront Condos vs. Single-Family Homes in Myrtle Beach

This is one of the most common conversations I have with out-of-state buyers, and the right answer changes a lot depending on what they actually want from a Myrtle Beach property. An oceanfront condo and a single-family home in Myrtle Beach are not just different in price. They're different in how they're used, how they're rented, how they're insured, and how they hold value through hurricane seasons and market cycles. After three decades of writing offers on both, I have a pretty clear sense of which buyer fits which path. Here's how I walk people through it.

What "Myrtle Beach" Means When You Compare the Two

First, some boundaries. When buyers say "Myrtle Beach," they usually mean the long strip along Ocean Boulevard, but the city limits stretch west to the Intracoastal Waterway and out toward Highway 501 and Carolina Forest. Oceanfront condos sit east of Highway 17 Business, almost always within a few blocks of the water. Single-family homes are scattered all over town, including beachfront streets in places like the Dunes Club, Pine Lakes, and the south end near Surfside, plus inland neighborhoods like Market Common, Carolina Forest, and Plantation Lakes.

Comparing the two isn't apples-to-apples because the locations themselves are doing a lot of work. A million dollars in an oceanfront condo and a million dollars in a Pine Lakes home are two very different lifestyles.

The Use Case for an Oceanfront Condo

Condos make the most sense when you want:

  • A lock-and-leave second home you can use a few weeks a year
  • A direct ocean view from the unit itself
  • Short-term rental income when you're not there
  • Minimal exterior maintenance, since the HOA handles roof, paint, pool, elevators, and landscaping

The investor side of this market is real. Plenty of oceanfront buildings allow daily and weekly rentals, and the rental peak runs roughly from mid-March through early September. The math depends heavily on building, view, floor, and bedroom count. A direct-oceanfront 2-bedroom in a strong rental building handles its monthly carry differently than a side-view efficiency in an aging building.

For buyers shopping the condo segment, the price bands roughly look like this in today's market:

  • Studio and 1-bedroom oceanfront units in older buildings: $150,000 to $260,000
  • 2-bedroom oceanfront in mid-tier buildings: $300,000 to $500,000
  • High-floor and luxury oceanfront: $500,000 to well past $1,000,000

If you're shopping the higher end, Myrtle Beach million-dollar homes include both single-family and the top oceanfront condo product, and seeing them side by side helps a lot of buyers decide which path fits.

The Use Case for a Single-Family Home

Single-family in Myrtle Beach makes sense when you want:

  • A primary residence, not a vacation property
  • Outdoor space, a garage, and a private yard
  • A neighborhood feel rather than a tower-and-elevator feel
  • Lower monthly HOA dues and more control over the property

The trade-off is location. Single-family inventory directly on the sand exists, but it's the most expensive product in the market by a wide margin. Most full-time Myrtle Beach single-family homes are inland a few blocks to a few miles, where buyers get newer construction, a real yard, and a community pool for a fraction of beachfront pricing.

For the most active price band, browse Myrtle Beach homes between $250,000 and $500,000. That range covers the bulk of new construction and resale single-family inventory inside the city right now.

Oceanfront Condos vs. Single-Family Homes in Myrtle Beach

How Insurance and HOA Dues Actually Compare

This is where buyer expectations get adjusted in my office. An oceanfront condo's monthly HOA fee can run $400 a month in older buildings and well over $1,200 a month in newer, amenity-heavy buildings. Those dues typically include the master insurance policy, water, sewer, trash, elevator maintenance, building staffing, pools, and exterior upkeep.

A single-family home doesn't carry that HOA load, but the owner has to budget directly for wind and hail insurance, flood insurance where applicable, roof reserves, HVAC, lawn care, and exterior paint cycles. The total cost of ownership often lands closer than buyers think — sometimes the condo is cheaper, sometimes the single-family is, depending on the property.

One specific trap: condo special assessments. When a building needs a roof, an elevator overhaul, or balcony repairs, the cost is split among unit owners. I've seen assessments range from a few hundred dollars to tens of thousands per unit. Always read the last two years of HOA meeting minutes and reserve study before going under contract.

Resale and Long-Term Hold

Both segments have appreciated meaningfully through the last cycle, but they don't move in sync. Oceanfront condo prices move with vacation demand, rental income, and insurance costs. Single-family prices move more with primary-resident demand, school zones, and interest rates. Holding both has actually been a smart play for some of my long-term clients, because they zig and zag at different times.

For higher-priced single-family product, Myrtle Beach homes between $500,000 and $1,000,000 tend to attract relocation buyers and move-up locals. That buyer pool is steadier than the vacation-rental crowd.

Two Things I Tell Buyers Choosing Between the Two

First, separate the lifestyle question from the investment question. If you'd actually use the property 6 to 8 weeks a year and want the income the other 30, you're a condo buyer. If you want a real home, a yard, a garage, and a community you'll see neighbors in, you're a single-family buyer. Trying to make one property do both jobs is where regret usually shows up.

Second, if rental income is part of the plan, never accept the first revenue estimate at face value. Cross-check it against actual rental history for that exact building or that exact block. I've watched too many buyers commit to a number from a listing agent that doesn't match what the unit has actually produced.

Key Takeaways

Oceanfront condos and Myrtle Beach single-family homes serve different jobs. Condos work for buyers who want low-maintenance second homes with rental upside on the water. Single-family homes work better for full-time residents who want space, yard, and a neighborhood. The total monthly cost of either is closer than buyers expect once you factor HOA dues, special assessment risk, wind and hail insurance, flood insurance, and reserve costs. The smartest move is to define how you'll actually use the property first, then let that decision steer the property type, not the other way around.

About Greg Harrelson

Greg Harrelson is a seasoned Realtor® with more than 30 years of experience serving the Myrtle Beach and Grand Strand markets. As the founder of Century 21 The Harrelson Group, Greg has built his career helping buyers, sellers, and investors achieve success in every corner of the coastal Carolina real estate market. His expertise spans residential homes, investment properties, land development, and coastal condos. Known for his deep local knowledge, innovative marketing strategies, and commitment to personal service, Greg consistently helps clients reach their real estate goals while navigating the ever-changing market with confidence and precision.
Posted in For Buyers
June 5, 2026

New Construction vs. Resale Homes in Horry County

This is one of the most common decisions buyers face when they shop Horry County, and the right answer isn't the same for everyone. New construction has been the headline story along Highway 905, Highway 544, and the Carolina Forest corridor for years now. At the same time, resale homes in older neighborhoods have quietly held their value and, in some pockets, outperformed the new builds. After watching both ends of this market through multiple cycles, here's how I help buyers decide which side fits.

New Construction vs. Resale Homes in Horry County

What "New Construction" Really Means in This Market

When buyers say new construction in Horry County, they usually mean a national builder like D.R. Horton, Lennar, Beazer, KB Home, Ryan, or Pulte putting up a community on raw land off a county road. The pace has been remarkable. Conway new construction has expanded by hundreds of homes a year between the Carsens Ferry, Astoria Park, and Highway 905 corridors, plus a heavy push into the Longs and Loris belt to the north.

Resale, by contrast, covers everything from a 1985 brick ranch on a half-acre lot in Conway proper to a 2018 Carolina Forest home that's been lived in for six years. Resale is the bigger pool by inventory, but it gets less marketing attention because individual sellers don't have the budget builders do.

Where New Construction Wins

New construction's biggest pull is what's behind the walls. You're getting current code, modern HVAC, foam insulation in most builds, and warranties that cover structural and mechanical issues for the first one to ten years depending on the builder. Energy bills are usually noticeably lower. The wind mitigation features built into 2024 and 2025 homes can carry meaningful insurance discounts in this coastal market.

New construction also tends to win on:

  • Buyer incentives, especially rate buydowns or closing cost contributions when builders need to move inventory
  • Predictable HOA covenants and amenity packages
  • Cleaner financing because the home is appraisal-friendly with comparable builder sales nearby
  • Lower immediate maintenance budget

Where Resale Quietly Wins

Resale wins on land, location, and character almost every time. A 1990s home on a true half-acre in Conway sits on a lot that today's builders rarely offer for the same price. Older neighborhoods have mature trees, established communities, and street layouts that the post-2015 cookie-cutter builds can't match.

You also see resale outperform new construction on:

  • Proximity to downtown Conway, Myrtle Beach city limits, and historic neighborhoods
  • True yard space, fenced backyards, and meaningful tree cover
  • Solid masonry construction in homes built in the 70s through early 90s
  • Settled foundations and predictable drainage that newer builds haven't proven yet

For buyers who want established neighborhoods with character, browsing Conway real estate resale inventory side by side with the new construction subdivisions is usually the most useful comparison. The price-per-square-foot numbers tell two different stories.

The Trap Buyers Fall Into With New Construction

I see a few patterns repeat year after year:

First, buyers assume the listing price is the negotiating ceiling. With most national builders, the listed base price is the floor for any given month, but the buyer incentives, lot premiums, and design center add-ons swing the final number much more than the base. Smart buyers ask which incentives are being offered this week, not just what's on the spec sheet.

Second, buyers under-budget the post-closing cost. New construction usually comes with no blinds, sparse landscaping, no fence, and no gutters. I've watched clients spend $15,000 to $30,000 in the first six months making the house live the way they wanted.

Third, the warranty isn't as bulletproof as buyers think. Cosmetic issues are usually fixed quickly, but settling cracks, drainage adjustments, and HVAC tuning can drag out. Document everything in writing during the walkthrough.

The Trap Buyers Fall Into With Resale

Resale has its own warning signs:

HVAC and roof age are the two budget killers I see most often on resale inspections. A 14-year-old roof or a 12-year-old HVAC system means the buyer is buying a project on top of a house. Build that into your offer.

The other resale trap is insurance. Older homes, especially those built before the mid-1990s, often miss out on wind mitigation credits that newer construction qualifies for automatically. Get the quote before you remove the inspection contingency. In Longs real estate and similar inland pockets the gap is smaller, but it still shows up on the policy.

How I Think About the Final Decision

If a buyer values predictability, low immediate maintenance, builder warranty, and modern energy efficiency, new construction usually fits. If a buyer values land, character, an established neighborhood, and a slightly lower entry price for the same square footage, resale usually fits.

One observation I've held for years: in this market, the resale homes that have been well-maintained by a long-term owner often outperform new construction over the next ownership cycle, because the new home stops being new the day you close. The buyer who sells the resale six years later isn't competing against fresh builder inventory the same way.

Key Takeaways

The new construction versus resale decision in Horry County is really a trade between predictability and character. New builds win on energy efficiency, warranties, insurance discounts, and clean financing. Resale wins on land, location, mature neighborhoods, and price per square foot in many pockets. The biggest mistakes buyers make are under-budgeting the post-closing costs on a new build and overlooking roof, HVAC, and insurance gaps on a resale. The right answer comes down to what you value in the house itself and how long you plan to own it. Buyers who hold for five to ten years should look hard at the resale side, because new construction stops being new the day the key changes hands.

About Greg Harrelson

Greg Harrelson is a seasoned Realtor® with more than 30 years of experience serving the Myrtle Beach and Grand Strand markets. As the founder of Century 21 The Harrelson Group, Greg has built his career helping buyers, sellers, and investors achieve success in every corner of the coastal Carolina real estate market. His expertise spans residential homes, investment properties, land development, and coastal condos. Known for his deep local knowledge, innovative marketing strategies, and commitment to personal service, Greg consistently helps clients reach their real estate goals while navigating the ever-changing market with confidence and precision.
June 4, 2026

Why Buyers Love Living Near Coastal Carolina University

Coastal Carolina University has done more to shape the Conway market in the last ten years than most people realize. When I started selling here in the early '90s, CCU was a quieter regional school. Today it's a Division I program, the campus has expanded across both sides of Highway 544, and there's a steady wave of buyers who specifically want to live within a short drive of it. Some are parents buying for a student. Some are alumni who came for school and never left. Some are investors who figured out that rent checks from college tenants don't bounce as often as people assume. Here's what that part of the Conway market actually looks like.

Where the CCU Area Sits in the Conway Market

CCU's main campus is off Highway 544 on the south side of Conway, sandwiched between the city proper and the Carolina Forest area. That location is the reason this part of town has grown faster than almost any other. You're 15 minutes from downtown Conway, 20 minutes to Myrtle Beach, and 10 minutes from Carolina Forest schools and shopping. The road network is the catch. Highway 544 carries a lot of traffic between campus, the beach, and the hospital corridor, especially between 7:45 and 9 a.m. and again at afternoon dismissal. If you live and work along it, you learn the cut-throughs quickly.

For shoppers, the most useful starting point is the broader Conway real estate map. CCU-adjacent inventory ranges from sub-$200,000 condos to half-million-dollar single-family builds, with a lot of activity in the $250,000 to $400,000 band.

Why Parents Buy Here

Parents who buy near CCU usually do the math like this: their child needs housing for four years, the dorm or apartment lease will run thousands a year, and Conway home prices are reasonable compared to the rest of the country. They buy a small home or a condo, the student lives there with a roommate, and the parents either sell when school ends or hold the property as a rental.

I've helped a lot of families through this exact scenario. The clients who end up happiest tend to do three things:

  • Buy something simple and durable, not the prettiest unit
  • Pick a community with reliable maintenance and security
  • Sign a real, written roommate lease, even between friends

Where Alumni and Faculty End Up

Alumni who graduated from CCU and decided to stay tend to drift to the historic side of Conway near Main Street, or into newer construction at Carsens Ferry and along the Highway 905 corridor. Faculty members often want a quieter commute and choose homes off the back roads toward Aynor. Several alumni families have also landed at Wild Wing Plantation when they want amenities, a golf course, and a true neighborhood feel. The pattern I've watched for years is that the people who fall in love with Conway as students usually want a real neighborhood once they buy, not a student-feeling community.

That's worth remembering as a buyer. Some communities near campus carry a steady student rental presence and the wear that comes with it. Others are full-time owner-occupied and you'd never know a university was nearby. Walk both during a weekday evening before you decide.

The Investor Angle on CCU

Investors have been a real part of this market for over a decade. The math has changed as prices climbed, but it still pencils out for the right property. Here's what I see working right now:

  • 2- and 3-bedroom condos in the $150,000 to $250,000 range with HOA dues that don't eat the cash flow
  • Older townhomes within walking distance of campus, especially in communities that allow long-term rentals
  • Small single-family homes with 3 or 4 bedrooms where each room can be leased separately to students

The key variable is HOA rental policy. Some communities have tightened up on rentals over the last few years, and a few cap the number of rentals allowed at any given time. I tell every investor client to request the HOA's current rental rules in writing before going under contract. Verbal answers from a leasing agent are not enough.

If you're looking at the condo side specifically, Conway condos for sale includes a number of buildings that have historically performed well with student tenants.

Lifestyle Pieces That Matter More Than Buyers Expect

Game days. CCU football and baseball weekends shift the entire south side of Conway. Streets close, traffic backs up, and parking gets creative. If you're a tailgater, it's a feature. If you work from home and need a quiet Saturday morning, plan around the home schedule.

The walkability question. Some communities near campus genuinely let students walk or bike to class. Others look close on a map but require a dangerous crossing of Highway 544. Don't assume from the listing photos. Drive the actual route.

The dining and grocery layer has caught up nicely. Conway Medical Center, the Costco on 501, the Tanger Outlets, and the restaurants near the campus give residents real options without driving to the beach. Five years ago that was not true.

Why Buyers Love Living Near Coastal Carolina University

Two Things I Tell Every CCU-Area Buyer

First, the academic calendar matters when you list a rental. Leases here run with the school year. If you close in November on a property you plan to rent, you may sit empty until August. Build that into your numbers.

Second, insurance and maintenance budgets on student-occupied homes need to be higher than a typical owner-occupied property. Things break faster. Floors take more abuse. Plan for it, and the investment still works. Pretend it won't happen, and it'll catch you the first year.

For families targeting nearby schools rather than the university, Astoria Park is another community worth a look, since its inventory and price points often overlap with what CCU-area buyers shop.

Key Takeaways

  • Coastal Carolina University shapes the south side of Conway more than most outside buyers realize
  • The market includes parents buying for students, alumni settling in, faculty, and long-term investors
  • Highway 544 traffic and CCU's home football and baseball schedule both affect daily life more than buyers expect
  • Investor success depends heavily on HOA rental rules and a realistic maintenance budget
  • Some communities feel like real neighborhoods and others feel like student housing - walk both at night before deciding
  • Inventory ranges from sub-$200,000 condos to $500,000+ single-family homes, with most activity in the $250,000-$400,000 band

About Greg Harrelson

Greg Harrelson is a seasoned Realtor® with more than 30 years of experience serving the Myrtle Beach and Grand Strand markets. As the founder of Century 21 The Harrelson Group, Greg has built his career helping buyers, sellers, and investors achieve success in every corner of the coastal Carolina real estate market. His expertise spans residential homes, investment properties, land development, and coastal condos. Known for his deep local knowledge, innovative marketing strategies, and commitment to personal service, Greg consistently helps clients reach their real estate goals while navigating the ever-changing market with confidence and precision.

Posted in For Buyers
June 3, 2026

Riverfront Living in Conway: What Buyers Need to Know

The Waccamaw River runs right through the back of our market, and the stretch that bends past downtown Conway is the part that surprises out-of-town buyers most. People drive down expecting saltwater. They roll into Conway thinking it's just another feeder town for Myrtle Beach. What they actually find is a slow, dark, blackwater river with cypress knees, paddleboarders, fishing skiffs, and a Riverwalk you can walk end to end before the coffee shops open. After thirty-plus years of selling in this area, I can tell you riverfront homes in Conway behave differently than oceanfront condos, and buyers who understand that early end up much happier with the home they pick.

Why Conway River Property Is Different

Most buyers I work with come down the coast looking at North Myrtle Beach, Myrtle Beach, or Garden City, and they only loop inland to Conway after a friend or family member tells them to. Once they're here, the first thing that grabs them is the price-per-foot of river footage versus ocean footage. A direct-Waccamaw home in Bucksport, off Pitch Landing, or up around the Bucksville area runs a fraction of an oceanfront equivalent. You also get a different lifestyle. The Waccamaw is freshwater for most of its run through Horry County, so owners don't fight the salt corrosion that oceanfront homeowners battle every season.

The other thing buyers learn quickly is that the river changes character every few miles. The stretch near Conway Marina sees the most boat traffic. South of town, near the Pitch Landing public boat launch, the homes are quieter and the cypress canopy is heavier. North toward Pireway Road and Highway 905, you cross into more remote acreage, which is where the buyers looking for real privacy tend to land.

Conway Riverfront Neighborhoods Worth Knowing

Conway riverfront real estate doesn't fall into tidy subdivisions the way coastal condo buildings do. A lot of it is one-off homes on bigger lots, mixed with a few planned communities. Wild Wing Plantation has a portion that fronts water, though most of its inventory is golf-course homes. You'll also find historic riverfront-adjacent properties near Kingston Lake (a Waccamaw tributary) inside the downtown Conway district, and newer construction on the north end where developers have been buying up family land.

If you're shopping the area, explore current Conway real estate listings and pay close attention to whether the water frontage is on the main Waccamaw channel or on a backwater slough. Both are beautiful, but only one supports a real dock and a powerboat.

Flood Zones, Dock Permits, and the Stuff Buyers Forget to Ask

Here's where I have to be direct: a lot of Conway's prettiest riverfront sits inside FEMA AE or A flood zones, and a few parcels touch the regulatory floodway itself. That matters because:

  • A floodway designation makes building or rebuilding more expensive, and sometimes nearly impossible.
  • An AE zone with a base flood elevation pushes your first finished floor up, which is why so many newer Conway river builds sit on tall pilings.
  • Lenders on a federally-backed loan require flood insurance, and the premium depends on elevation, not just the zone.

The 2015 and 2016 floods are still very much in local memory. I had clients lose homes back then, and I had clients sell two years later for higher than pre-flood pricing. The Conway market is forgiving over time, but you need to buy the right elevation, not just the right view.

Dock permits are the second thing buyers underestimate. SCDHEC and the U.S. Army Corps of Engineers both have a hand in what you can build on the bank. A grandfathered, permitted dock that conveys with the home is gold. Building a new one can take six months to a year and isn't guaranteed.

Riverfront Living in Conway What Buyers Need to Know

What These Homes Cost and Who's Buying

Realistic price bands in the Conway market right now:

  • Older river cottage on a smaller lot: low $300s to mid $400s
  • Solid mid-tier riverfront on usable acreage with a dock: $500s to $700s
  • Custom riverfront with deep water and a boathouse: $800s and up, sometimes well past a million depending on land

The buyer pool is split. A lot are retirees from Pennsylvania, Ohio, and New York who priced oceanfront condos, did the math on HOA dues, and pivoted inland. A growing share are remote workers who want trees, water, and a short drive to Myrtle Beach International. A smaller group are local move-up buyers who already owned in Carolina Forest or Aynor and finally pulled the trigger on a river property.

For lower-maintenance options that still keep you close to the water, take a look at Conway condos for sale. They aren't on the river, but several put you within walking distance of the Riverwalk and the public boat ramp.

Two Things I Tell Every River Buyer

One: read the seller's disclosure twice. Conway is an old town, and a lot of these homes have lived through hurricanes, lightning strikes, and septic upgrades. The real story is usually in the disclosure.

Two: walk the property in the rain. I'm serious. The river is one part of the picture. The yard's drainage, the driveway pitch, and where the water pools after a heavy storm tell you more than a sunny-day showing ever will.

If you want to be near the water without the full floodplain complexity, no-HOA homes in Conway often sit on higher ground a mile or two off the river. Those are worth a long look.

Key Takeaways

Riverfront in Conway is its own market, distinct from the coast and from inland Horry County. You're trading salt for freshwater, surf for cypress trees, and HOA dues for septic maintenance. The right home, on the right elevation, on the right stretch of the Waccamaw, holds value through high water and low. The wrong lot can punish you on insurance, permits, and resale. The biggest win is buying with eyes wide open: confirm the flood zone, confirm the dock permit, and lean on an agent who has watched this market through more than one storm cycle.

Frequently Asked Questions

Do I need flood insurance for a Conway riverfront home?

If the home sits in an AE or A flood zone and you're using a federally-backed mortgage, yes, flood insurance is required. Even outside those zones, voluntary coverage along the Waccamaw is smart. Premiums depend heavily on the home's elevation above the base flood line, so two homes on the same street can have very different rates.

Can I build a new dock on the Waccamaw River?

You can apply, but expect the process to take six months to a year. SCDHEC and the U.S. Army Corps of Engineers both review dock permits, and the rules are stricter on certain stretches. A home that already conveys with a permitted dock is significantly more valuable than a similar home without one.

Is the Waccamaw River saltwater or freshwater near Conway?

The river is freshwater through most of Conway and only turns tidal and brackish as you head south toward Bucksport and Wachesaw. That matters for fishing, boat maintenance, and dock construction. Freshwater is much easier on outboard motors and metal hardware.

How are property taxes calculated on Conway riverfront homes?

South Carolina taxes primary residences at a 4 percent assessment ratio and second homes or investment properties at 6 percent. The same physical home can carry very different tax bills depending on how it is used and whether the owner files for the legal residence exemption with Horry County.

Are short-term rentals allowed on Conway riverfront property?

Short-term rental rules vary by jurisdiction within Conway and Horry County. Some river roads sit inside the city limits, others are unincorporated county. Always confirm with the planning office before counting on Airbnb or VRBO income.

About Greg Harrelson

Greg Harrelson is a seasoned Realtor® with more than 30 years of experience serving the Myrtle Beach and Grand Strand markets. As the founder of Century 21 The Harrelson Group, Greg has built his career helping buyers, sellers, and investors achieve success in every corner of the coastal Carolina real estate market. His expertise spans residential homes, investment properties, land development, and coastal condos. Known for his deep local knowledge, innovative marketing strategies, and commitment to personal service, Greg consistently helps clients reach their real estate goals while navigating the ever-changing market with confidence and precision.